- The loan loss exclusion. Loss resulting from the complete or partial nonpayment of or default on any loan or extension of credit is excluded, whether the loan was procured in good faith or through trick, artifice, fraud or false pretenses, except to the extent the loss is covered under the fidelity agreement, the forgery agreement or the fraudulent mortgage documents clause. The exclusion is the single most litigated provision in financial institution bond law, and the courts have generally enforced it against lenders who attempt to recast underwriting failures as fraud (Clore 2008). The mortgage bankers bond’s fraudulent documents clause is the industry’s negotiated carve back, and its scope defines how much origination fraud is actually insured.
- Indirect and consequential loss. Loss of income, loss of potential income including interest and dividends not realized, damages for which the insured is liable to third parties except as specifically covered, and costs, fees and expenses incurred in establishing the existence or amount of a loss are excluded. The repurchase demand that follows an investor’s discovery of a fraudulent loan is a liability of the insured to a third party, which is why the modern forms’ express extension of fidelity coverage to repurchase and indemnification loss arising from employee dishonesty is a material enhancement and not a drafting nicety.
- Prior knowledge and the termination as to employee clause. The bond does not cover loss caused by an employee after the insured has learned of any dishonest act committed by that employee, at any time, in the insured’s service or elsewhere. A mortgage banker that rehires a loan officer dismissed by a competitor for application fraud has, in most forms, uninsured that loan officer from the day of hire. The same principle applies to a principal whose prior dishonesty was known to the other owners.
- Trading, market and valuation loss. Loss resulting from the fluctuation in the market value of loans or servicing rights, from hedging activity, from the exercise of secondary marketing judgment, or from the movement of interest rates is excluded, because it is the business of the mortgage banker and not a fidelity event.
- Fines, penalties and regulatory loss. Civil money penalties, consumer restitution ordered by a regulator, and the cost of responding to an examination are excluded from the bond and are the province of professional liability and regulatory coverage, if insured at all.
- Nonemployee and nonauthorized actors. Loss caused by a borrower, a broker, a correspondent or an appraiser acting alone is not fidelity loss; it is covered, if at all, only through the forgery, fraudulent documents or closing agent agreements and their sublimits. The mortgage banker that sources production through a third party origination channel carries a structurally different exposure from the retail lender, and the underwriter will examine the channel mix for exactly that reason.
The mortgage impairment distinction belongs here as well. The E&O section responds to the servicer’s negligent failure to perform an enumerated duty. It does not respond to the collateral loss itself where the servicer performed the duty and the borrower’s hazard carrier simply failed, nor to physical loss on a property the servicer was never obliged to insure. Those are mortgage impairment risks, and a servicer with a significant portfolio of loans in catastrophe exposed markets will carry a mortgage impairment policy alongside the mortgage bankers bond rather than in place of it.
The boundary, then, is coherent. The bond pays when a covered person steals, forges or lies, or when the servicer negligently fails to protect the security it holds for others. It does not pay when the borrower cannot pay, when the market moves, when the regulator fines, or when the insured’s own management chose to look away. A risk program built with that boundary in view will place credit risk with the investor and the mortgage insurer, market risk with the hedge, regulatory risk with the professional liability carrier, and fidelity and servicing errors risk with the mortgage bankers bond, each in its proper place.
Underwriting the Mortgage Banker
The fidelity underwriter does not price a mortgage bankers bond from the limit alone. The limit is the investor’s number; the premium is a function of the insured’s control environment, its funding structure and its servicing book, and the submission that produces a competitive quote is the submission that lets the underwriter see those three things clearly. Surety One’s underwriting review of a mortgage banker concentrates on the following.
- Ownership and management. Who owns the insured, whether any owner or officer has been the subject of investor suspension, FHA Mortgagee Review Board action, state licensing discipline or a prior fidelity claim, and whether the principals’ personal financial condition creates the pressure that precedes owner dishonesty. Because the investor guides require the principal owner to be a covered employee, the principal is underwritten as a fidelity risk in his own right.
- Internal controls over funds. Dual authorization on wires, callback verification of closing instructions and payoff statements against independently sourced contact information, segregation of the people who fund loans from the people who reconcile warehouse and custodial accounts, daily reconciliation of custodial P&I and T&I accounts, and the frequency and independence of the control audit. Funds transfer fraud is now the dominant loss, and the controls over outgoing wires are the dominant rating factor.
- Warehouse facilities. The number of lines, their aggregate capacity, whether funding is wet or dry, the collateral custodian arrangements and the bailee letter mechanics, and the lender’s own collateral audit findings. A lender that has had a collateral exception or a line reduction in the prior twenty four months is a materially different risk.
- Channel mix. The proportion of retail, consumer direct, wholesale broker and correspondent production, because nonemployee origination channels carry forgery and fraudulent documents exposure outside the fidelity agreement and inside the sublimits.
- Quality control. The prefunding and postclosing QC programs the investor guides require, the independence of the QC function from production, the defect rates reported to Fannie Mae and Freddie Mac, the early payment default history and the volume and disposition of repurchase and indemnification demands over the prior three years.
- Servicing portfolio. Owned and subserviced UPB by investor, escrow administration practices, flood zone determination vendor, hazard and flood tracking vendor, force placed insurance practices and tax service arrangements. The E&O half of the bond is priced almost entirely from this data.
- Licensing and approvals. Current NMLS licensure in each state of operation, the state license surety bonds in force, FHA mortgagee approval, VA, USDA and Ginnie Mae issuer status, and the GSE seller/servicer approvals with their most recent eligibility review.
- Financial condition. Audited statements, adjusted net worth against the investor minimums, liquidity, the mix of gain on sale and servicing income, and the trend in both, because a mortgage banker under financial strain is the setting in which both owner dishonesty and servicing neglect occur.
From that review the underwriter structures the bond: the aggregate against the investor formulas, the sub-limits against the actual forgery, closing agent and funds transfer exposures rather than the market’s defaults, the deductible against the net worth ceiling and the insured’s retention appetite, and the endorsement schedule against every warehouse agreement and investor approval the insured holds. The result is a mortgage bankers bond that will be accepted by the investors on its face and will respond when the insured needs it, which are not the same test and are too often treated as if they were.
The Mortgage Bankers Bond Is Not the State License Bond
The word bond invites a confusion that this essay would be incomplete without addressing. Every state that licenses mortgage lenders, mortgage brokers and mortgage loan originators under the SAFE Act framework requires a surety bond as a condition of licensure, filed through the Nationwide Multistate Licensing System (NMLS) and sized by statute or by the licensee’s origination volume. That instrument is a surety bond in the classical sense: a three party contract in which the surety guarantees to the state, as obligee, that the licensee will comply with the licensing statute, with the licensee bound to indemnify the surety for any loss paid. It protects borrowers and the regulator against the licensee’s misconduct; it protects the licensee against nothing. The surety expects no loss and prices the bond as credit, not as risk transfer. The mechanics of that relationship are the subject of The Contractor’s Guide to Surety Bonds and apply to the mortgage license bond as fully as to any other.
The mortgage bankers bond is the opposite instrument in every respect that matters. It is a two party contract of insurance between the mortgage banker and the carrier. It protects the mortgage banker and the parties the mortgage banker designates, not the public. It is required by investors and warehouse lenders rather than by statute. It contemplates loss and is priced to pay it. The fact that the fidelity section carries the vocabulary of the surety industry, bond rather than policy, is a historical artifact of the fidelity and surety companies that wrote the first blanket bonds, and it misleads lenders every year into believing that the license bond they filed with the state satisfies the warehouse lender’s fidelity requirement, or that the mortgage bankers bond they bought from their broker satisfies the state. Neither is true.
A licensed mortgage banker carries both. Surety One writes both, and the state by state requirements for the license bonds are collected in our current practitioner’s guide, Mortgage Industry Surety Bonds, available without charge at constantinpoindexterauthor.com/publications.
The mortgage bankers bond is a composite of three distinct contracts of indemnity that happen to share a declarations page: a blanket fidelity bond descended from the Form 24 and extended to owners, closing agents and investor funds; a set of mortgage specific insuring agreements that address forgery, fraudulent instruments, custodial funds and funds transfer; and a first party mortgagee’s errors and omissions section that insures the lender’s security against its own servicing negligence. Wrapped around the whole is an endorsement schedule that converts warehouse lenders and investors into protected parties and that must be reconciled, at every renewal, against the current text of the Fannie Mae Selling Guide, the Ginnie Mae MBS Guide and the warehouse agreements in force. Each component has its own trigger, its own measure of loss and its own exclusions, and the boundary between all of them and uninsurable credit risk is the loan loss exclusion and the manifest intent standard that the courts have enforced for forty years.
A mortgage banker that understands this structure will buy a better bond, will present itself to its warehouse lenders and investors as a better risk, and will know on the day a loss is discovered which insuring agreement applies and what the proof of loss must show. A fidelity underwriter that understands it will structure and price the bond to the insured’s actual exposures rather than to the investor’s minimum, and will be the counterparty the insured wants on the other end of the claim.
Surety One, Inc. underwrites the mortgage bankers bond for originators, servicers, issuers and correspondents nationwide, together with the state mortgage license surety bonds that accompany it. Underwriting inquiries and submissions may be directed to MortgageBankersBond.com, to Underwriting@SuretyOne.com, or to an underwriter at (919) 859-5294.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- Clore, Duncan L., ed. 2008. Financial Institution Bonds. 3rd ed. Chicago: American Bar Association, Tort Trial and Insurance Practice Section.
- Fannie Mae. 2017a. Selling Guide A3-5-01, Fidelity Bond and Errors and Omissions Coverage Provisions. https://selling-guide.fanniemae.com/sel/a3-5-01/fidelity-bond-and-errors-and-omissions-coverage-provisions
- Fannie Mae. 2017b. Selling Guide A3-5-02, Fidelity Bond Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-02/fidelity-bond-policy-requirements
- Fannie Mae. 2017c. Selling Guide A3-5-03, Errors and Omissions Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-03/errors-and-omissions-policy-requirements
- Fannie Mae. 2017d. Servicing Guide Announcement SVC-2017-07, Fidelity Bond and Errors and Omissions Insurance Requirements. https://singlefamily.fanniemae.com/media/20246/display
- Freddie Mac. 2023. Multifamily Seller/Servicer Guide, Chapter 3, Section 3.16, Seller/Servicer’s Fidelity and Errors & Omissions Insurance Coverage. https://mf.freddiemac.com/docs/chapters/mf_guide_ch_3.pdf
- Freddie Mac. 2024. Become a Freddie Mac Single-Family Seller/Servicer: Document Checklist. https://my.sf.freddiemac.com/docs/pdf/forms/become_ss_customer_document_checklist.pdf
- Ginnie Mae. 2014. Mortgage-Backed Securities Guide, HUD Handbook 5500.3, Rev. 1, Chapter 2, Section 2-7, Fidelity Bond and Errors and Omissions Insurance. https://www.ginniemae.gov/doing_business_with_ginniemae/issuer_resources/MBSGuideLib/Chapter_02.pdf
- Ginnie Mae. 2018. All Participants Memorandum APM 18-06, Fidelity Bond and E&O Insurance Requirements. https://www.ginniemae.gov/memorandum/apm/fidelity-bond-and-eo-insurance-requirements-apm-18-06
- Ginnie Mae. 2024. All Participants Memorandum APM 24-04, Ginnie Mae Central Application for Issuer Insurance and Audited Financial Statements. https://ginniemae.gov/issuers/program_guidelines/Lists/MBSGuideAPMsLib/Attachments/160/APM_24-04.pdf
- Massachusetts Housing Finance Agency. 761 CMR 20.00, Eligibility Guide for Sellers and Servicers. https://www.mass.gov/doc/761-cmr-20-eligibility-guide/download
- Poindexter, C. Constantin. 2025. The Contractor’s Guide to Surety Bonds. Amazon and Barnes & Noble.
- Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000).
- Surety One, Inc. 2026. Mortgage Bankers Bond (Blanket Fidelity Bond). https://suretyone.com/mortgage-bankers-bond-blanket-fidelity-bond
- Total UPB of $100mn or less: $300,000.
- Over $100mn up to $1bn: $300,000 plus 0.150 percent of the next $400mn plus 0.125 percent of the next $500mn.
- Over $1bn: the foregoing plus 0.100 percent of the amount over $1bn.
- Maximum required fidelity coverage: $150mn.
The maximum deductible for seller/servicers with UPB of $1bn or less is the higher of 10 percent of the face amount or $100,000; above $1bn it is 15 percent, with a larger deductible available only on Fannie Mae’s prior written consent and in no event exceeding 1 percent of the seller/servicer’s net worth (Fannie Mae 2017b). The errors and omissions coverage must equal the fidelity coverage so computed, but Fannie Mae does not require E&O above $10mn for a single family only seller/servicer or $30mn for one that sells or services both single family and multifamily loans; per loan E&O policies are accepted if the insurer’s liability per loan at least equals the highest UPB of any loan the seller/servicer owns, with a per loan deductible no greater than 5 percent, and aggregate E&O deductibles follow the same 10 percent or $100,000 and 15 percent schedule as the fidelity bond (Fannie Mae 2017c). A subsidiary may rely on its parent’s bond if it is a joint insured, Lloyd’s affiliated coverage is acceptable, and the seller/servicer must report any single fidelity or E&O loss that is mortgage related within 30 days of discovery (Fannie Mae 2017a; Fannie Mae 2017d).
Ginnie Mae’s requirements, in Chapter 2 of the Mortgage-Backed Securities Guide (HUD Handbook 5500.3, Rev. 1), begin from a $300,000 minimum for both the fidelity bond and the mortgagee’s E&O policy, written either per loss or in the aggregate, and scale with the issuer’s total servicing portfolio, including Fannie Mae, Freddie Mac, private label and portfolio loans: 0.15 percent of the portfolio between $100mn and $500mn, 0.125 percent between $500mn and $1bn, and 0.1 percent above $1bn, so that a $500mn portfolio requires $900,000, a $1bn portfolio $1.525mn, and a $1.5bn portfolio $2.025mn (Ginnie Mae 2014). Ginnie Mae historically capped the E&O requirement at $20mn and permits a fidelity cap below the formula where the issuer demonstrates that the government sponsored enterprises have capped its coverage (Ginnie Mae 2014). In 2018 Ginnie Mae realigned its coverage and deductible standards with the enterprise schedule for policies and renewals on and after January 1, 2019, eliminated its separate loss payable endorsement requirement as redundant of its direct claim and direct payment rights, and began requiring issuers to upload the complete bond and E&O policy, not merely certificates, through its issuer portal (Ginnie Mae 2018); the 2024 revisions moved that submission to Ginnie Mae Central and made the full policy with all endorsements the standard evidence of coverage at every renewal (Ginnie Mae 2024). The carrier must be rated B+ or better by A.M. Best and licensed or authorized where the collateral properties lie (Ginnie Mae 2014).
Freddie Mac’s single family requirements parallel Fannie Mae’s in structure and are enforced at the point of approval, where the applicant must deliver the declarations pages of both its fidelity bond and its errors and omissions policy together with its warehouse agreements (Freddie Mac 2024); its Multifamily Seller/Servicer Guide carries a dedicated section on fidelity and E&O coverage with its own notice obligations (Freddie Mac 2023). State housing finance agencies that purchase or master service loans impose comparable formulas, Massachusetts being a published example that ties fidelity coverage to a percentage of the servicing portfolio and sets a $1mn E&O floor (MassHousing 761 CMR 20).
The operational lesson is that the limit must be recomputed at every renewal against the originator’s trailing twelve month production and its month end owned servicing peak, that the deductible must be tested against both the percentage ceiling and the net worth ceiling, and that the endorsements must be refreshed against the current text of each guide. A bond that was compliant when bound can fall out of compliance in a single strong quarter of originations.
Exclusions and the Credit Risk Boundary
Every fidelity instrument draws a line between the risk the surety will carry and the risk that belongs to the insured’s own business judgment, and in the mortgage bankers bond that line separates fidelity and errors risk from credit risk. The exclusions that enforce it are not boilerplate; they are the negotiated perimeter of the product, and the mortgage banker that understands them will structure its operations so that its real exposures fall inside the perimeter rather than outside it.
- The loan loss exclusion. Loss resulting from the complete or partial nonpayment of or default on any loan or extension of credit is excluded, whether the loan was procured in good faith or through trick, artifice, fraud or false pretenses, except to the extent the loss is covered under the fidelity agreement, the forgery agreement or the fraudulent mortgage documents clause. The exclusion is the single most litigated provision in financial institution bond law, and the courts have generally enforced it against lenders who attempt to recast underwriting failures as fraud (Clore 2008). The mortgage bankers bond’s fraudulent documents clause is the industry’s negotiated carve back, and its scope defines how much origination fraud is actually insured.
- Indirect and consequential loss. Loss of income, loss of potential income including interest and dividends not realized, damages for which the insured is liable to third parties except as specifically covered, and costs, fees and expenses incurred in establishing the existence or amount of a loss are excluded. The repurchase demand that follows an investor’s discovery of a fraudulent loan is a liability of the insured to a third party, which is why the modern forms’ express extension of fidelity coverage to repurchase and indemnification loss arising from employee dishonesty is a material enhancement and not a drafting nicety.
- Prior knowledge and the termination as to employee clause. The bond does not cover loss caused by an employee after the insured has learned of any dishonest act committed by that employee, at any time, in the insured’s service or elsewhere. A mortgage banker that rehires a loan officer dismissed by a competitor for application fraud has, in most forms, uninsured that loan officer from the day of hire. The same principle applies to a principal whose prior dishonesty was known to the other owners.
- Trading, market and valuation loss. Loss resulting from the fluctuation in the market value of loans or servicing rights, from hedging activity, from the exercise of secondary marketing judgment, or from the movement of interest rates is excluded, because it is the business of the mortgage banker and not a fidelity event.
- Fines, penalties and regulatory loss. Civil money penalties, consumer restitution ordered by a regulator, and the cost of responding to an examination are excluded from the bond and are the province of professional liability and regulatory coverage, if insured at all.
- Nonemployee and nonauthorized actors. Loss caused by a borrower, a broker, a correspondent or an appraiser acting alone is not fidelity loss; it is covered, if at all, only through the forgery, fraudulent documents or closing agent agreements and their sublimits. The mortgage banker that sources production through a third party origination channel carries a structurally different exposure from the retail lender, and the underwriter will examine the channel mix for exactly that reason.
The mortgage impairment distinction belongs here as well. The E&O section responds to the servicer’s negligent failure to perform an enumerated duty. It does not respond to the collateral loss itself where the servicer performed the duty and the borrower’s hazard carrier simply failed, nor to physical loss on a property the servicer was never obliged to insure. Those are mortgage impairment risks, and a servicer with a significant portfolio of loans in catastrophe exposed markets will carry a mortgage impairment policy alongside the mortgage bankers bond rather than in place of it.
The boundary, then, is coherent. The bond pays when a covered person steals, forges or lies, or when the servicer negligently fails to protect the security it holds for others. It does not pay when the borrower cannot pay, when the market moves, when the regulator fines, or when the insured’s own management chose to look away. A risk program built with that boundary in view will place credit risk with the investor and the mortgage insurer, market risk with the hedge, regulatory risk with the professional liability carrier, and fidelity and servicing errors risk with the mortgage bankers bond, each in its proper place.
Underwriting the Mortgage Banker
The fidelity underwriter does not price a mortgage bankers bond from the limit alone. The limit is the investor’s number; the premium is a function of the insured’s control environment, its funding structure and its servicing book, and the submission that produces a competitive quote is the submission that lets the underwriter see those three things clearly. Surety One’s underwriting review of a mortgage banker concentrates on the following.
- Ownership and management. Who owns the insured, whether any owner or officer has been the subject of investor suspension, FHA Mortgagee Review Board action, state licensing discipline or a prior fidelity claim, and whether the principals’ personal financial condition creates the pressure that precedes owner dishonesty. Because the investor guides require the principal owner to be a covered employee, the principal is underwritten as a fidelity risk in his own right.
- Internal controls over funds. Dual authorization on wires, callback verification of closing instructions and payoff statements against independently sourced contact information, segregation of the people who fund loans from the people who reconcile warehouse and custodial accounts, daily reconciliation of custodial P&I and T&I accounts, and the frequency and independence of the control audit. Funds transfer fraud is now the dominant loss, and the controls over outgoing wires are the dominant rating factor.
- Warehouse facilities. The number of lines, their aggregate capacity, whether funding is wet or dry, the collateral custodian arrangements and the bailee letter mechanics, and the lender’s own collateral audit findings. A lender that has had a collateral exception or a line reduction in the prior twenty four months is a materially different risk.
- Channel mix. The proportion of retail, consumer direct, wholesale broker and correspondent production, because nonemployee origination channels carry forgery and fraudulent documents exposure outside the fidelity agreement and inside the sublimits.
- Quality control. The prefunding and postclosing QC programs the investor guides require, the independence of the QC function from production, the defect rates reported to Fannie Mae and Freddie Mac, the early payment default history and the volume and disposition of repurchase and indemnification demands over the prior three years.
- Servicing portfolio. Owned and subserviced UPB by investor, escrow administration practices, flood zone determination vendor, hazard and flood tracking vendor, force placed insurance practices and tax service arrangements. The E&O half of the bond is priced almost entirely from this data.
- Licensing and approvals. Current NMLS licensure in each state of operation, the state license surety bonds in force, FHA mortgagee approval, VA, USDA and Ginnie Mae issuer status, and the GSE seller/servicer approvals with their most recent eligibility review.
- Financial condition. Audited statements, adjusted net worth against the investor minimums, liquidity, the mix of gain on sale and servicing income, and the trend in both, because a mortgage banker under financial strain is the setting in which both owner dishonesty and servicing neglect occur.
From that review the underwriter structures the bond: the aggregate against the investor formulas, the sub-limits against the actual forgery, closing agent and funds transfer exposures rather than the market’s defaults, the deductible against the net worth ceiling and the insured’s retention appetite, and the endorsement schedule against every warehouse agreement and investor approval the insured holds. The result is a mortgage bankers bond that will be accepted by the investors on its face and will respond when the insured needs it, which are not the same test and are too often treated as if they were.
The Mortgage Bankers Bond Is Not the State License Bond
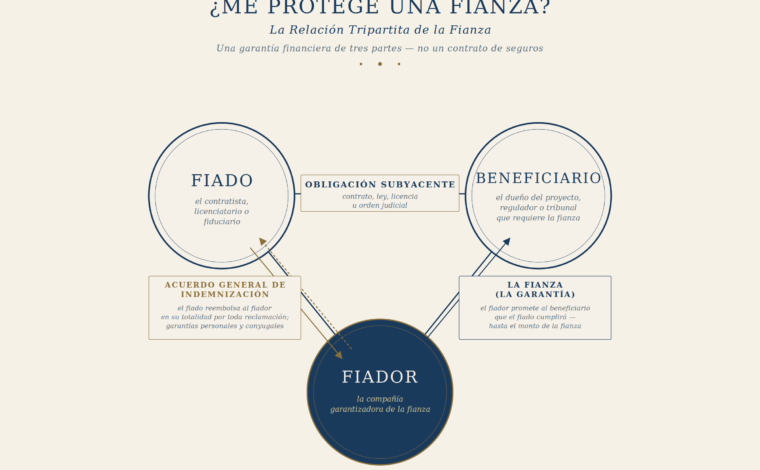
The word bond invites a confusion that this essay would be incomplete without addressing. Every state that licenses mortgage lenders, mortgage brokers and mortgage loan originators under the SAFE Act framework requires a surety bond as a condition of licensure, filed through the Nationwide Multistate Licensing System (NMLS) and sized by statute or by the licensee’s origination volume. That instrument is a surety bond in the classical sense: a three party contract in which the surety guarantees to the state, as obligee, that the licensee will comply with the licensing statute, with the licensee bound to indemnify the surety for any loss paid. It protects borrowers and the regulator against the licensee’s misconduct; it protects the licensee against nothing. The surety expects no loss and prices the bond as credit, not as risk transfer. The mechanics of that relationship are the subject of The Contractor’s Guide to Surety Bonds and apply to the mortgage license bond as fully as to any other.
The mortgage bankers bond is the opposite instrument in every respect that matters. It is a two party contract of insurance between the mortgage banker and the carrier. It protects the mortgage banker and the parties the mortgage banker designates, not the public. It is required by investors and warehouse lenders rather than by statute. It contemplates loss and is priced to pay it. The fact that the fidelity section carries the vocabulary of the surety industry, bond rather than policy, is a historical artifact of the fidelity and surety companies that wrote the first blanket bonds, and it misleads lenders every year into believing that the license bond they filed with the state satisfies the warehouse lender’s fidelity requirement, or that the mortgage bankers bond they bought from their broker satisfies the state. Neither is true.
A licensed mortgage banker carries both. Surety One writes both, and the state by state requirements for the license bonds are collected in our current practitioner’s guide, Mortgage Industry Surety Bonds, available without charge at constantinpoindexterauthor.com/publications.
The mortgage bankers bond is a composite of three distinct contracts of indemnity that happen to share a declarations page: a blanket fidelity bond descended from the Form 24 and extended to owners, closing agents and investor funds; a set of mortgage specific insuring agreements that address forgery, fraudulent instruments, custodial funds and funds transfer; and a first party mortgagee’s errors and omissions section that insures the lender’s security against its own servicing negligence. Wrapped around the whole is an endorsement schedule that converts warehouse lenders and investors into protected parties and that must be reconciled, at every renewal, against the current text of the Fannie Mae Selling Guide, the Ginnie Mae MBS Guide and the warehouse agreements in force. Each component has its own trigger, its own measure of loss and its own exclusions, and the boundary between all of them and uninsurable credit risk is the loan loss exclusion and the manifest intent standard that the courts have enforced for forty years.
A mortgage banker that understands this structure will buy a better bond, will present itself to its warehouse lenders and investors as a better risk, and will know on the day a loss is discovered which insuring agreement applies and what the proof of loss must show. A fidelity underwriter that understands it will structure and price the bond to the insured’s actual exposures rather than to the investor’s minimum, and will be the counterparty the insured wants on the other end of the claim.
Surety One, Inc. underwrites the mortgage bankers bond for originators, servicers, issuers and correspondents nationwide, together with the state mortgage license surety bonds that accompany it. Underwriting inquiries and submissions may be directed to MortgageBankersBond.com, to Underwriting@SuretyOne.com, or to an underwriter at (919) 859-5294.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- Clore, Duncan L., ed. 2008. Financial Institution Bonds. 3rd ed. Chicago: American Bar Association, Tort Trial and Insurance Practice Section.
- Fannie Mae. 2017a. Selling Guide A3-5-01, Fidelity Bond and Errors and Omissions Coverage Provisions. https://selling-guide.fanniemae.com/sel/a3-5-01/fidelity-bond-and-errors-and-omissions-coverage-provisions
- Fannie Mae. 2017b. Selling Guide A3-5-02, Fidelity Bond Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-02/fidelity-bond-policy-requirements
- Fannie Mae. 2017c. Selling Guide A3-5-03, Errors and Omissions Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-03/errors-and-omissions-policy-requirements
- Fannie Mae. 2017d. Servicing Guide Announcement SVC-2017-07, Fidelity Bond and Errors and Omissions Insurance Requirements. https://singlefamily.fanniemae.com/media/20246/display
- Freddie Mac. 2023. Multifamily Seller/Servicer Guide, Chapter 3, Section 3.16, Seller/Servicer’s Fidelity and Errors & Omissions Insurance Coverage. https://mf.freddiemac.com/docs/chapters/mf_guide_ch_3.pdf
- Freddie Mac. 2024. Become a Freddie Mac Single-Family Seller/Servicer: Document Checklist. https://my.sf.freddiemac.com/docs/pdf/forms/become_ss_customer_document_checklist.pdf
- Ginnie Mae. 2014. Mortgage-Backed Securities Guide, HUD Handbook 5500.3, Rev. 1, Chapter 2, Section 2-7, Fidelity Bond and Errors and Omissions Insurance. https://www.ginniemae.gov/doing_business_with_ginniemae/issuer_resources/MBSGuideLib/Chapter_02.pdf
- Ginnie Mae. 2018. All Participants Memorandum APM 18-06, Fidelity Bond and E&O Insurance Requirements. https://www.ginniemae.gov/memorandum/apm/fidelity-bond-and-eo-insurance-requirements-apm-18-06
- Ginnie Mae. 2024. All Participants Memorandum APM 24-04, Ginnie Mae Central Application for Issuer Insurance and Audited Financial Statements. https://ginniemae.gov/issuers/program_guidelines/Lists/MBSGuideAPMsLib/Attachments/160/APM_24-04.pdf
- Massachusetts Housing Finance Agency. 761 CMR 20.00, Eligibility Guide for Sellers and Servicers. https://www.mass.gov/doc/761-cmr-20-eligibility-guide/download
- Poindexter, C. Constantin. 2025. The Contractor’s Guide to Surety Bonds. Amazon and Barnes & Noble.
- Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000).
- Surety One, Inc. 2026. Mortgage Bankers Bond (Blanket Fidelity Bond). https://suretyone.com/mortgage-bankers-bond-blanket-fidelity-bond
- Additional insured or joint loss payee status. The warehouse lender, and often each investor with which the originator has a purchase agreement, is named by endorsement so that the lender’s loss of money or collateral through the originator’s employee dishonesty, forgery or theft is a covered loss and the proceeds are payable to the lender as its interest appears. Fannie Mae reserves the same rights for itself in the policy provisions it requires (Fannie Mae 2017a). The drafting matters: a bare loss payee clause gives the lender a right to proceeds the insured has already established; an additional insured clause gives the lender its own claim.
- Direct claim and direct payment. Ginnie Mae requires that it have the right to file a claim directly with the insurer and be paid directly by the insurer, and that it be named on the loss draft where its interest is affected (Ginnie Mae 2014). Sophisticated warehouse lenders negotiate the same right, so that the originator’s insolvency or indifference does not stand between the lender and the bond.
- Notice of cancellation, reduction and restrictive modification. The warehouse lender’s protection is only as good as its knowledge that the bond is in force. The endorsement obligates the insurer to give the lender advance written notice, thirty days being the industry convention and the term Surety One’s own program literature has long described for Fannie Mae, before the bond is cancelled, the aggregate is reduced other than by payment of loss, or coverage is restricted (Surety One 2026). Fannie Mae’s policy provisions and reporting requirements track the same concept, requiring the seller/servicer to notify it of cancellation, reduction, nonrenewal or restrictive modification (Fannie Mae 2017a; Fannie Mae 2017d), and Ginnie Mae requires that it be notified whether the change is for cause or at the issuer’s request (Ginnie Mae 2014).
- Owner and principal dishonesty. As discussed above, the investor guides require the principal owner to be a covered employee. The warehouse lender’s endorsement usually goes a step further and confirms that the lender’s recovery is not defeated by the fact that the dishonest actor controlled the insured, which is precisely the double pledging and double selling scenario the lender fears most. A mortgage bankers bond that excludes loss caused by any owner or partner, or that conditions coverage on the dishonesty being unknown to management, offers the warehouse lender nothing in the case that matters.
Two further structural points deserve notice. The first is that the warehouse lender’s protection under the originator’s bond is derivative: it is limited by the originator’s aggregate, eroded by the originator’s other losses, and subject to the originator’s compliance with the notice and proof of loss conditions. Warehouse lenders with large correspondent networks therefore buy their own mortgage investor bond, a distinct instrument that treats the employees of approved correspondents as employees of the warehouse lender and carries a fraudulent mortgage clause written from the purchaser’s side. The second is that the warehouse lender’s endorsement and the investor’s required provisions are not interchangeable, and the mortgage banker that carries three warehouse lines and sells to five investors will carry an endorsement schedule that must be reconciled at every renewal. That reconciliation is underwriting work, and it is the service a specialist underwriter provides that a certificate mill does not.
Investor Mandates: Fannie Mae, Freddie Mac and Ginnie Mae
The limits on a mortgage bankers bond are not chosen; they are computed. Each of the three principal secondary market counterparties publishes a formula, a cap and a deductible ceiling, and the bond must satisfy the most demanding of the formulas that apply to the insured’s approvals.
Fannie Mae’s requirements, consolidated into the Selling Guide in 2017 after nearly two decades without material revision, measure the required fidelity coverage against the greater of the seller/servicer’s annual total unpaid principal balance of single family and multifamily originations or its highest monthly total UPB of loans it owns and services, including loans it owns that are subserviced by others (Fannie Mae 2017b). The schedule is cumulative:
- Total UPB of $100mn or less: $300,000.
- Over $100mn up to $1bn: $300,000 plus 0.150 percent of the next $400mn plus 0.125 percent of the next $500mn.
- Over $1bn: the foregoing plus 0.100 percent of the amount over $1bn.
- Maximum required fidelity coverage: $150mn.
The maximum deductible for seller/servicers with UPB of $1bn or less is the higher of 10 percent of the face amount or $100,000; above $1bn it is 15 percent, with a larger deductible available only on Fannie Mae’s prior written consent and in no event exceeding 1 percent of the seller/servicer’s net worth (Fannie Mae 2017b). The errors and omissions coverage must equal the fidelity coverage so computed, but Fannie Mae does not require E&O above $10mn for a single family only seller/servicer or $30mn for one that sells or services both single family and multifamily loans; per loan E&O policies are accepted if the insurer’s liability per loan at least equals the highest UPB of any loan the seller/servicer owns, with a per loan deductible no greater than 5 percent, and aggregate E&O deductibles follow the same 10 percent or $100,000 and 15 percent schedule as the fidelity bond (Fannie Mae 2017c). A subsidiary may rely on its parent’s bond if it is a joint insured, Lloyd’s affiliated coverage is acceptable, and the seller/servicer must report any single fidelity or E&O loss that is mortgage related within 30 days of discovery (Fannie Mae 2017a; Fannie Mae 2017d).
Ginnie Mae’s requirements, in Chapter 2 of the Mortgage-Backed Securities Guide (HUD Handbook 5500.3, Rev. 1), begin from a $300,000 minimum for both the fidelity bond and the mortgagee’s E&O policy, written either per loss or in the aggregate, and scale with the issuer’s total servicing portfolio, including Fannie Mae, Freddie Mac, private label and portfolio loans: 0.15 percent of the portfolio between $100mn and $500mn, 0.125 percent between $500mn and $1bn, and 0.1 percent above $1bn, so that a $500mn portfolio requires $900,000, a $1bn portfolio $1.525mn, and a $1.5bn portfolio $2.025mn (Ginnie Mae 2014). Ginnie Mae historically capped the E&O requirement at $20mn and permits a fidelity cap below the formula where the issuer demonstrates that the government sponsored enterprises have capped its coverage (Ginnie Mae 2014). In 2018 Ginnie Mae realigned its coverage and deductible standards with the enterprise schedule for policies and renewals on and after January 1, 2019, eliminated its separate loss payable endorsement requirement as redundant of its direct claim and direct payment rights, and began requiring issuers to upload the complete bond and E&O policy, not merely certificates, through its issuer portal (Ginnie Mae 2018); the 2024 revisions moved that submission to Ginnie Mae Central and made the full policy with all endorsements the standard evidence of coverage at every renewal (Ginnie Mae 2024). The carrier must be rated B+ or better by A.M. Best and licensed or authorized where the collateral properties lie (Ginnie Mae 2014).
Freddie Mac’s single family requirements parallel Fannie Mae’s in structure and are enforced at the point of approval, where the applicant must deliver the declarations pages of both its fidelity bond and its errors and omissions policy together with its warehouse agreements (Freddie Mac 2024); its Multifamily Seller/Servicer Guide carries a dedicated section on fidelity and E&O coverage with its own notice obligations (Freddie Mac 2023). State housing finance agencies that purchase or master service loans impose comparable formulas, Massachusetts being a published example that ties fidelity coverage to a percentage of the servicing portfolio and sets a $1mn E&O floor (MassHousing 761 CMR 20).
The operational lesson is that the limit must be recomputed at every renewal against the originator’s trailing twelve month production and its month end owned servicing peak, that the deductible must be tested against both the percentage ceiling and the net worth ceiling, and that the endorsements must be refreshed against the current text of each guide. A bond that was compliant when bound can fall out of compliance in a single strong quarter of originations.
Exclusions and the Credit Risk Boundary
Every fidelity instrument draws a line between the risk the surety will carry and the risk that belongs to the insured’s own business judgment, and in the mortgage bankers bond that line separates fidelity and errors risk from credit risk. The exclusions that enforce it are not boilerplate; they are the negotiated perimeter of the product, and the mortgage banker that understands them will structure its operations so that its real exposures fall inside the perimeter rather than outside it.
- The loan loss exclusion. Loss resulting from the complete or partial nonpayment of or default on any loan or extension of credit is excluded, whether the loan was procured in good faith or through trick, artifice, fraud or false pretenses, except to the extent the loss is covered under the fidelity agreement, the forgery agreement or the fraudulent mortgage documents clause. The exclusion is the single most litigated provision in financial institution bond law, and the courts have generally enforced it against lenders who attempt to recast underwriting failures as fraud (Clore 2008). The mortgage bankers bond’s fraudulent documents clause is the industry’s negotiated carve back, and its scope defines how much origination fraud is actually insured.
- Indirect and consequential loss. Loss of income, loss of potential income including interest and dividends not realized, damages for which the insured is liable to third parties except as specifically covered, and costs, fees and expenses incurred in establishing the existence or amount of a loss are excluded. The repurchase demand that follows an investor’s discovery of a fraudulent loan is a liability of the insured to a third party, which is why the modern forms’ express extension of fidelity coverage to repurchase and indemnification loss arising from employee dishonesty is a material enhancement and not a drafting nicety.
- Prior knowledge and the termination as to employee clause. The bond does not cover loss caused by an employee after the insured has learned of any dishonest act committed by that employee, at any time, in the insured’s service or elsewhere. A mortgage banker that rehires a loan officer dismissed by a competitor for application fraud has, in most forms, uninsured that loan officer from the day of hire. The same principle applies to a principal whose prior dishonesty was known to the other owners.
- Trading, market and valuation loss. Loss resulting from the fluctuation in the market value of loans or servicing rights, from hedging activity, from the exercise of secondary marketing judgment, or from the movement of interest rates is excluded, because it is the business of the mortgage banker and not a fidelity event.
- Fines, penalties and regulatory loss. Civil money penalties, consumer restitution ordered by a regulator, and the cost of responding to an examination are excluded from the bond and are the province of professional liability and regulatory coverage, if insured at all.
- Nonemployee and nonauthorized actors. Loss caused by a borrower, a broker, a correspondent or an appraiser acting alone is not fidelity loss; it is covered, if at all, only through the forgery, fraudulent documents or closing agent agreements and their sublimits. The mortgage banker that sources production through a third party origination channel carries a structurally different exposure from the retail lender, and the underwriter will examine the channel mix for exactly that reason.
The mortgage impairment distinction belongs here as well. The E&O section responds to the servicer’s negligent failure to perform an enumerated duty. It does not respond to the collateral loss itself where the servicer performed the duty and the borrower’s hazard carrier simply failed, nor to physical loss on a property the servicer was never obliged to insure. Those are mortgage impairment risks, and a servicer with a significant portfolio of loans in catastrophe exposed markets will carry a mortgage impairment policy alongside the mortgage bankers bond rather than in place of it.
The boundary, then, is coherent. The bond pays when a covered person steals, forges or lies, or when the servicer negligently fails to protect the security it holds for others. It does not pay when the borrower cannot pay, when the market moves, when the regulator fines, or when the insured’s own management chose to look away. A risk program built with that boundary in view will place credit risk with the investor and the mortgage insurer, market risk with the hedge, regulatory risk with the professional liability carrier, and fidelity and servicing errors risk with the mortgage bankers bond, each in its proper place.
Underwriting the Mortgage Banker
The fidelity underwriter does not price a mortgage bankers bond from the limit alone. The limit is the investor’s number; the premium is a function of the insured’s control environment, its funding structure and its servicing book, and the submission that produces a competitive quote is the submission that lets the underwriter see those three things clearly. Surety One’s underwriting review of a mortgage banker concentrates on the following.
- Ownership and management. Who owns the insured, whether any owner or officer has been the subject of investor suspension, FHA Mortgagee Review Board action, state licensing discipline or a prior fidelity claim, and whether the principals’ personal financial condition creates the pressure that precedes owner dishonesty. Because the investor guides require the principal owner to be a covered employee, the principal is underwritten as a fidelity risk in his own right.
- Internal controls over funds. Dual authorization on wires, callback verification of closing instructions and payoff statements against independently sourced contact information, segregation of the people who fund loans from the people who reconcile warehouse and custodial accounts, daily reconciliation of custodial P&I and T&I accounts, and the frequency and independence of the control audit. Funds transfer fraud is now the dominant loss, and the controls over outgoing wires are the dominant rating factor.
- Warehouse facilities. The number of lines, their aggregate capacity, whether funding is wet or dry, the collateral custodian arrangements and the bailee letter mechanics, and the lender’s own collateral audit findings. A lender that has had a collateral exception or a line reduction in the prior twenty four months is a materially different risk.
- Channel mix. The proportion of retail, consumer direct, wholesale broker and correspondent production, because nonemployee origination channels carry forgery and fraudulent documents exposure outside the fidelity agreement and inside the sublimits.
- Quality control. The prefunding and postclosing QC programs the investor guides require, the independence of the QC function from production, the defect rates reported to Fannie Mae and Freddie Mac, the early payment default history and the volume and disposition of repurchase and indemnification demands over the prior three years.
- Servicing portfolio. Owned and subserviced UPB by investor, escrow administration practices, flood zone determination vendor, hazard and flood tracking vendor, force placed insurance practices and tax service arrangements. The E&O half of the bond is priced almost entirely from this data.
- Licensing and approvals. Current NMLS licensure in each state of operation, the state license surety bonds in force, FHA mortgagee approval, VA, USDA and Ginnie Mae issuer status, and the GSE seller/servicer approvals with their most recent eligibility review.
- Financial condition. Audited statements, adjusted net worth against the investor minimums, liquidity, the mix of gain on sale and servicing income, and the trend in both, because a mortgage banker under financial strain is the setting in which both owner dishonesty and servicing neglect occur.
From that review the underwriter structures the bond: the aggregate against the investor formulas, the sub-limits against the actual forgery, closing agent and funds transfer exposures rather than the market’s defaults, the deductible against the net worth ceiling and the insured’s retention appetite, and the endorsement schedule against every warehouse agreement and investor approval the insured holds. The result is a mortgage bankers bond that will be accepted by the investors on its face and will respond when the insured needs it, which are not the same test and are too often treated as if they were.
The Mortgage Bankers Bond Is Not the State License Bond
The word bond invites a confusion that this essay would be incomplete without addressing. Every state that licenses mortgage lenders, mortgage brokers and mortgage loan originators under the SAFE Act framework requires a surety bond as a condition of licensure, filed through the Nationwide Multistate Licensing System (NMLS) and sized by statute or by the licensee’s origination volume. That instrument is a surety bond in the classical sense: a three party contract in which the surety guarantees to the state, as obligee, that the licensee will comply with the licensing statute, with the licensee bound to indemnify the surety for any loss paid. It protects borrowers and the regulator against the licensee’s misconduct; it protects the licensee against nothing. The surety expects no loss and prices the bond as credit, not as risk transfer. The mechanics of that relationship are the subject of The Contractor’s Guide to Surety Bonds and apply to the mortgage license bond as fully as to any other.
The mortgage bankers bond is the opposite instrument in every respect that matters. It is a two party contract of insurance between the mortgage banker and the carrier. It protects the mortgage banker and the parties the mortgage banker designates, not the public. It is required by investors and warehouse lenders rather than by statute. It contemplates loss and is priced to pay it. The fact that the fidelity section carries the vocabulary of the surety industry, bond rather than policy, is a historical artifact of the fidelity and surety companies that wrote the first blanket bonds, and it misleads lenders every year into believing that the license bond they filed with the state satisfies the warehouse lender’s fidelity requirement, or that the mortgage bankers bond they bought from their broker satisfies the state. Neither is true.
A licensed mortgage banker carries both. Surety One writes both, and the state by state requirements for the license bonds are collected in our current practitioner’s guide, Mortgage Industry Surety Bonds, available without charge at constantinpoindexterauthor.com/publications.
The mortgage bankers bond is a composite of three distinct contracts of indemnity that happen to share a declarations page: a blanket fidelity bond descended from the Form 24 and extended to owners, closing agents and investor funds; a set of mortgage specific insuring agreements that address forgery, fraudulent instruments, custodial funds and funds transfer; and a first party mortgagee’s errors and omissions section that insures the lender’s security against its own servicing negligence. Wrapped around the whole is an endorsement schedule that converts warehouse lenders and investors into protected parties and that must be reconciled, at every renewal, against the current text of the Fannie Mae Selling Guide, the Ginnie Mae MBS Guide and the warehouse agreements in force. Each component has its own trigger, its own measure of loss and its own exclusions, and the boundary between all of them and uninsurable credit risk is the loan loss exclusion and the manifest intent standard that the courts have enforced for forty years.
A mortgage banker that understands this structure will buy a better bond, will present itself to its warehouse lenders and investors as a better risk, and will know on the day a loss is discovered which insuring agreement applies and what the proof of loss must show. A fidelity underwriter that understands it will structure and price the bond to the insured’s actual exposures rather than to the investor’s minimum, and will be the counterparty the insured wants on the other end of the claim.
Surety One, Inc. underwrites the mortgage bankers bond for originators, servicers, issuers and correspondents nationwide, together with the state mortgage license surety bonds that accompany it. Underwriting inquiries and submissions may be directed to MortgageBankersBond.com, to Underwriting@SuretyOne.com, or to an underwriter at (919) 859-5294.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- Clore, Duncan L., ed. 2008. Financial Institution Bonds. 3rd ed. Chicago: American Bar Association, Tort Trial and Insurance Practice Section.
- Fannie Mae. 2017a. Selling Guide A3-5-01, Fidelity Bond and Errors and Omissions Coverage Provisions. https://selling-guide.fanniemae.com/sel/a3-5-01/fidelity-bond-and-errors-and-omissions-coverage-provisions
- Fannie Mae. 2017b. Selling Guide A3-5-02, Fidelity Bond Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-02/fidelity-bond-policy-requirements
- Fannie Mae. 2017c. Selling Guide A3-5-03, Errors and Omissions Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-03/errors-and-omissions-policy-requirements
- Fannie Mae. 2017d. Servicing Guide Announcement SVC-2017-07, Fidelity Bond and Errors and Omissions Insurance Requirements. https://singlefamily.fanniemae.com/media/20246/display
- Freddie Mac. 2023. Multifamily Seller/Servicer Guide, Chapter 3, Section 3.16, Seller/Servicer’s Fidelity and Errors & Omissions Insurance Coverage. https://mf.freddiemac.com/docs/chapters/mf_guide_ch_3.pdf
- Freddie Mac. 2024. Become a Freddie Mac Single-Family Seller/Servicer: Document Checklist. https://my.sf.freddiemac.com/docs/pdf/forms/become_ss_customer_document_checklist.pdf
- Ginnie Mae. 2014. Mortgage-Backed Securities Guide, HUD Handbook 5500.3, Rev. 1, Chapter 2, Section 2-7, Fidelity Bond and Errors and Omissions Insurance. https://www.ginniemae.gov/doing_business_with_ginniemae/issuer_resources/MBSGuideLib/Chapter_02.pdf
- Ginnie Mae. 2018. All Participants Memorandum APM 18-06, Fidelity Bond and E&O Insurance Requirements. https://www.ginniemae.gov/memorandum/apm/fidelity-bond-and-eo-insurance-requirements-apm-18-06
- Ginnie Mae. 2024. All Participants Memorandum APM 24-04, Ginnie Mae Central Application for Issuer Insurance and Audited Financial Statements. https://ginniemae.gov/issuers/program_guidelines/Lists/MBSGuideAPMsLib/Attachments/160/APM_24-04.pdf
- Massachusetts Housing Finance Agency. 761 CMR 20.00, Eligibility Guide for Sellers and Servicers. https://www.mass.gov/doc/761-cmr-20-eligibility-guide/download
- Poindexter, C. Constantin. 2025. The Contractor’s Guide to Surety Bonds. Amazon and Barnes & Noble.
- Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000).
- Surety One, Inc. 2026. Mortgage Bankers Bond (Blanket Fidelity Bond). https://suretyone.com/mortgage-bankers-bond-blanket-fidelity-bond
- Forgery or alteration of mortgage instruments. The blanket bond’s forgery agreement was written for checks and drafts. The mortgage bankers bond extends it to promissory notes, mortgages and deeds of trust, assignments, satisfactions and releases, and modification agreements, and the better forms now expressly reach electronically signed and electronically notarized documents. The covered event is the insured’s good faith reliance on an instrument that bears a forged signature or has been materially altered. The loss is measured by the insured’s interest in the instrument, not by the credit quality of the borrower.
- Fraudulent mortgage documents. Closely related but analytically distinct is coverage for loss sustained through the insured’s good faith reliance on a mortgage or note that is genuine on its face but fraudulently procured: the straw buyer, the identity theft refinance, the fictitious property. This clause is the mortgage industry’s answer to the loan exclusion, and it is deliberately narrow. It typically requires that the fraud be in the execution of the instrument or the identity of the mortgagor, not in the borrower’s financial representations, and it is subject to its own sublimit in many forms.
- Failure to record. Negligent failure to record or perfect a security instrument, or to obtain a required lien position, is an errors exposure rather than a dishonesty exposure, and on many forms it sits in the E&O section. Wherever it sits, the loss covered is the impairment of the insured’s or investor’s lien, not the loan balance.
- Closing agent dishonesty. Mortgage bankers fund through settlement agents and closing attorneys who are not employees. The bond extends fidelity style coverage to the theft or misapplication of loan proceeds by the closing agent, which is the exposure that a wet funding warehouse line creates every time a wire leaves the lender before the recorded instrument is in hand.
- Theft of investor or warehouse lender funds and collateral. This is the clause that the warehouse market reads first. It covers the loss of money or collateral belonging to a warehouse lender or secondary market investor, including the original note, while in the insured’s custody, and it is the insuring agreement that the warehouse lender’s additional insured or loss payee endorsement attaches to.
- Custodial and escrow accounts. A servicer holds principal and interest and taxes and insurance funds in custodial accounts that belong to investors and borrowers. The misappropriation of those funds by an employee is fidelity loss under Insuring Agreement A, but the mortgage bankers bond typically names the custodial exposure specifically and confirms that the investor’s interest in the funds is a covered interest.
- Computer systems and funds transfer fraud. Fraudulent instructions that cause the insured, or its warehouse bank, to wire closing funds to an impostor’s account are now the most frequent severity loss in the sector. The coverage grants vary enormously in quality: some forms respond only to unauthorized entry into the insured’s own system, others respond to social engineering that induces an authorized employee to act, and the difference between the two is the difference between a paid claim and a declination.
- Documents in transit. The original note and the collateral file travel between the originator, the document custodian, the warehouse lender’s bailee and the investor. Loss or destruction of those documents in transit, and the cost of reconstitution, is addressed by a transit agreement adapted from the Form 24’s Insuring Agreement C.
Two points of underwriting discipline follow. First, these agreements are frequently sub-limited below the aggregate, and the investor guides measure compliance against the fidelity and E&O limits only; a bond with an adequate aggregate but a $100,000 forgery sublimit may satisfy Fannie Mae and still leave a $3mn funding fraud largely uninsured. Second, the agreements overlap and the bond’s single loss and non-cumulation provisions decide which limit applies when a single scheme implicates several of them. An employee who forges an assignment to divert a warehouse lender’s collateral has committed fidelity loss, forgery loss and theft of collateral in one act, and the bond will pay once.
The Errors and Omissions Component: Mortgagee’s E&O Is Not Professional Liability
The second half of the mortgage bankers bond is routinely misdescribed, by brokers and by lenders alike, as errors and omissions insurance in the sense a lawyer or an accountant would recognize. It is not. Mortgagee’s errors and omissions coverage is a first party property style coverage that indemnifies the mortgagee, and the investors whose interests it carries, for the impairment of the mortgage security caused by the mortgagee’s own negligent failure to perform specific servicing duties. It does not defend the lender against a borrower’s lawsuit, it does not respond to a regulatory investigation, and it does not pay a third party’s damages. Those exposures belong to a separate mortgage bankers professional liability policy, which is a claims made liability contract with a duty to defend and which no investor guide requires.
The servicing duties that mortgagee’s E&O insures are enumerated in the investor guides and have been stable for decades. Fannie Mae requires that the policy protect the seller/servicer at least against negligence, errors and omissions in maintaining property and flood insurance on the collateral, maintaining required mortgage insurance or loan guaranty, determining whether a property lies in a Special Flood Hazard Area, paying real estate taxes and special assessments, and complying with the reporting requirements of the mortgage insurer or guarantor (Fannie Mae 2017c). Ginnie Mae’s list is the same in substance, framed around FHA insurance and VA, RD and PIH guaranties and around the issuer’s duty to keep the mortgaged property insured in accordance with the MBS Guide (Ginnie Mae 2014). The classic mortgagee’s E&O form expresses these as separate insuring agreements: hazard insurance, flood insurance, real estate tax, mortgage guaranty insurance, life and disability insurance on the mortgagor where the mortgage requires it, and loss of or damage to the mortgagee’s interest in the property or documents.
The loss paid under each agreement is the mortgagee’s actual loss of security. If a servicer allows the hazard policy to lapse and the house burns, the E&O agreement pays what the hazard carrier would have paid, less the deductible, to the extent of the mortgagee’s interest. If the servicer fails to pay the taxes and the county’s tax deed extinguishes the lien, the agreement pays the lien that was lost. If the servicer fails to maintain the FHA insurance and the loan defaults, the agreement pays the claim HUD would have paid. This is why Fannie Mae will accept a mortgage impairment or mortgagee interest policy in substitution for a stand alone E&O policy provided it delivers substantially the same coverage (Fannie Mae 2017c): the two products insure the same interest by different mechanisms. Mortgage impairment insurance is written on a per loan basis and responds to physical loss to the collateral when the servicer’s required insurance has failed; mortgagee’s E&O is written on an aggregate basis and responds to the servicer’s negligent act, whatever the collateral’s fate.
The practical consequences for the mortgage banker are three. First, because the E&O section pays the mortgagee’s loss of security and not a liability judgment, its limit need not and should not be sized to litigation exposure; the investor guides tie it to the fidelity limit for a reason. Second, because the covered duties are servicing duties, an originator that sells servicing released and retains no portfolio has a materially smaller E&O exposure than a servicer with a $2bn book of escrowed loans, and the underwriter will price accordingly even though the investor’s minimum limit is the same. Third, because the E&O section is first party, the investor’s rights under it are rights to the proceeds, which is why the loss payee and direct claim provisions discussed below reach both halves of the bond.
Warehouse Lender and Investor Amendments
A mortgage banker funds with other people’s money. The warehouse lender advances the closing funds against a security interest in the note and mortgage, takes delivery of the original note under a bailee letter or through a document custodian, and is repaid when the loan is sold to the investor, typically within thirty to sixty days. During that interval the warehouse lender’s collateral is a piece of paper in the originator’s or custodian’s possession, and the originator’s employees and principals control the flow of funds in and out. The warehouse lender therefore underwrites the originator’s fidelity program as carefully as it underwrites the originator’s balance sheet, and it conditions the line on amendments to the mortgage bankers bond that convert the lender from a stranger to the contract into a protected party.
The amendments are of four kinds, and the underwriter who writes mortgage bankers bonds must be fluent in each.
- Additional insured or joint loss payee status. The warehouse lender, and often each investor with which the originator has a purchase agreement, is named by endorsement so that the lender’s loss of money or collateral through the originator’s employee dishonesty, forgery or theft is a covered loss and the proceeds are payable to the lender as its interest appears. Fannie Mae reserves the same rights for itself in the policy provisions it requires (Fannie Mae 2017a). The drafting matters: a bare loss payee clause gives the lender a right to proceeds the insured has already established; an additional insured clause gives the lender its own claim.
- Direct claim and direct payment. Ginnie Mae requires that it have the right to file a claim directly with the insurer and be paid directly by the insurer, and that it be named on the loss draft where its interest is affected (Ginnie Mae 2014). Sophisticated warehouse lenders negotiate the same right, so that the originator’s insolvency or indifference does not stand between the lender and the bond.
- Notice of cancellation, reduction and restrictive modification. The warehouse lender’s protection is only as good as its knowledge that the bond is in force. The endorsement obligates the insurer to give the lender advance written notice, thirty days being the industry convention and the term Surety One’s own program literature has long described for Fannie Mae, before the bond is cancelled, the aggregate is reduced other than by payment of loss, or coverage is restricted (Surety One 2026). Fannie Mae’s policy provisions and reporting requirements track the same concept, requiring the seller/servicer to notify it of cancellation, reduction, nonrenewal or restrictive modification (Fannie Mae 2017a; Fannie Mae 2017d), and Ginnie Mae requires that it be notified whether the change is for cause or at the issuer’s request (Ginnie Mae 2014).
- Owner and principal dishonesty. As discussed above, the investor guides require the principal owner to be a covered employee. The warehouse lender’s endorsement usually goes a step further and confirms that the lender’s recovery is not defeated by the fact that the dishonest actor controlled the insured, which is precisely the double pledging and double selling scenario the lender fears most. A mortgage bankers bond that excludes loss caused by any owner or partner, or that conditions coverage on the dishonesty being unknown to management, offers the warehouse lender nothing in the case that matters.
Two further structural points deserve notice. The first is that the warehouse lender’s protection under the originator’s bond is derivative: it is limited by the originator’s aggregate, eroded by the originator’s other losses, and subject to the originator’s compliance with the notice and proof of loss conditions. Warehouse lenders with large correspondent networks therefore buy their own mortgage investor bond, a distinct instrument that treats the employees of approved correspondents as employees of the warehouse lender and carries a fraudulent mortgage clause written from the purchaser’s side. The second is that the warehouse lender’s endorsement and the investor’s required provisions are not interchangeable, and the mortgage banker that carries three warehouse lines and sells to five investors will carry an endorsement schedule that must be reconciled at every renewal. That reconciliation is underwriting work, and it is the service a specialist underwriter provides that a certificate mill does not.
Investor Mandates: Fannie Mae, Freddie Mac and Ginnie Mae
The limits on a mortgage bankers bond are not chosen; they are computed. Each of the three principal secondary market counterparties publishes a formula, a cap and a deductible ceiling, and the bond must satisfy the most demanding of the formulas that apply to the insured’s approvals.
Fannie Mae’s requirements, consolidated into the Selling Guide in 2017 after nearly two decades without material revision, measure the required fidelity coverage against the greater of the seller/servicer’s annual total unpaid principal balance of single family and multifamily originations or its highest monthly total UPB of loans it owns and services, including loans it owns that are subserviced by others (Fannie Mae 2017b). The schedule is cumulative:
- Total UPB of $100mn or less: $300,000.
- Over $100mn up to $1bn: $300,000 plus 0.150 percent of the next $400mn plus 0.125 percent of the next $500mn.
- Over $1bn: the foregoing plus 0.100 percent of the amount over $1bn.
- Maximum required fidelity coverage: $150mn.
The maximum deductible for seller/servicers with UPB of $1bn or less is the higher of 10 percent of the face amount or $100,000; above $1bn it is 15 percent, with a larger deductible available only on Fannie Mae’s prior written consent and in no event exceeding 1 percent of the seller/servicer’s net worth (Fannie Mae 2017b). The errors and omissions coverage must equal the fidelity coverage so computed, but Fannie Mae does not require E&O above $10mn for a single family only seller/servicer or $30mn for one that sells or services both single family and multifamily loans; per loan E&O policies are accepted if the insurer’s liability per loan at least equals the highest UPB of any loan the seller/servicer owns, with a per loan deductible no greater than 5 percent, and aggregate E&O deductibles follow the same 10 percent or $100,000 and 15 percent schedule as the fidelity bond (Fannie Mae 2017c). A subsidiary may rely on its parent’s bond if it is a joint insured, Lloyd’s affiliated coverage is acceptable, and the seller/servicer must report any single fidelity or E&O loss that is mortgage related within 30 days of discovery (Fannie Mae 2017a; Fannie Mae 2017d).
Ginnie Mae’s requirements, in Chapter 2 of the Mortgage-Backed Securities Guide (HUD Handbook 5500.3, Rev. 1), begin from a $300,000 minimum for both the fidelity bond and the mortgagee’s E&O policy, written either per loss or in the aggregate, and scale with the issuer’s total servicing portfolio, including Fannie Mae, Freddie Mac, private label and portfolio loans: 0.15 percent of the portfolio between $100mn and $500mn, 0.125 percent between $500mn and $1bn, and 0.1 percent above $1bn, so that a $500mn portfolio requires $900,000, a $1bn portfolio $1.525mn, and a $1.5bn portfolio $2.025mn (Ginnie Mae 2014). Ginnie Mae historically capped the E&O requirement at $20mn and permits a fidelity cap below the formula where the issuer demonstrates that the government sponsored enterprises have capped its coverage (Ginnie Mae 2014). In 2018 Ginnie Mae realigned its coverage and deductible standards with the enterprise schedule for policies and renewals on and after January 1, 2019, eliminated its separate loss payable endorsement requirement as redundant of its direct claim and direct payment rights, and began requiring issuers to upload the complete bond and E&O policy, not merely certificates, through its issuer portal (Ginnie Mae 2018); the 2024 revisions moved that submission to Ginnie Mae Central and made the full policy with all endorsements the standard evidence of coverage at every renewal (Ginnie Mae 2024). The carrier must be rated B+ or better by A.M. Best and licensed or authorized where the collateral properties lie (Ginnie Mae 2014).
Freddie Mac’s single family requirements parallel Fannie Mae’s in structure and are enforced at the point of approval, where the applicant must deliver the declarations pages of both its fidelity bond and its errors and omissions policy together with its warehouse agreements (Freddie Mac 2024); its Multifamily Seller/Servicer Guide carries a dedicated section on fidelity and E&O coverage with its own notice obligations (Freddie Mac 2023). State housing finance agencies that purchase or master service loans impose comparable formulas, Massachusetts being a published example that ties fidelity coverage to a percentage of the servicing portfolio and sets a $1mn E&O floor (MassHousing 761 CMR 20).
The operational lesson is that the limit must be recomputed at every renewal against the originator’s trailing twelve month production and its month end owned servicing peak, that the deductible must be tested against both the percentage ceiling and the net worth ceiling, and that the endorsements must be refreshed against the current text of each guide. A bond that was compliant when bound can fall out of compliance in a single strong quarter of originations.
Exclusions and the Credit Risk Boundary
Every fidelity instrument draws a line between the risk the surety will carry and the risk that belongs to the insured’s own business judgment, and in the mortgage bankers bond that line separates fidelity and errors risk from credit risk. The exclusions that enforce it are not boilerplate; they are the negotiated perimeter of the product, and the mortgage banker that understands them will structure its operations so that its real exposures fall inside the perimeter rather than outside it.
- The loan loss exclusion. Loss resulting from the complete or partial nonpayment of or default on any loan or extension of credit is excluded, whether the loan was procured in good faith or through trick, artifice, fraud or false pretenses, except to the extent the loss is covered under the fidelity agreement, the forgery agreement or the fraudulent mortgage documents clause. The exclusion is the single most litigated provision in financial institution bond law, and the courts have generally enforced it against lenders who attempt to recast underwriting failures as fraud (Clore 2008). The mortgage bankers bond’s fraudulent documents clause is the industry’s negotiated carve back, and its scope defines how much origination fraud is actually insured.
- Indirect and consequential loss. Loss of income, loss of potential income including interest and dividends not realized, damages for which the insured is liable to third parties except as specifically covered, and costs, fees and expenses incurred in establishing the existence or amount of a loss are excluded. The repurchase demand that follows an investor’s discovery of a fraudulent loan is a liability of the insured to a third party, which is why the modern forms’ express extension of fidelity coverage to repurchase and indemnification loss arising from employee dishonesty is a material enhancement and not a drafting nicety.
- Prior knowledge and the termination as to employee clause. The bond does not cover loss caused by an employee after the insured has learned of any dishonest act committed by that employee, at any time, in the insured’s service or elsewhere. A mortgage banker that rehires a loan officer dismissed by a competitor for application fraud has, in most forms, uninsured that loan officer from the day of hire. The same principle applies to a principal whose prior dishonesty was known to the other owners.
- Trading, market and valuation loss. Loss resulting from the fluctuation in the market value of loans or servicing rights, from hedging activity, from the exercise of secondary marketing judgment, or from the movement of interest rates is excluded, because it is the business of the mortgage banker and not a fidelity event.
- Fines, penalties and regulatory loss. Civil money penalties, consumer restitution ordered by a regulator, and the cost of responding to an examination are excluded from the bond and are the province of professional liability and regulatory coverage, if insured at all.
- Nonemployee and nonauthorized actors. Loss caused by a borrower, a broker, a correspondent or an appraiser acting alone is not fidelity loss; it is covered, if at all, only through the forgery, fraudulent documents or closing agent agreements and their sublimits. The mortgage banker that sources production through a third party origination channel carries a structurally different exposure from the retail lender, and the underwriter will examine the channel mix for exactly that reason.
The mortgage impairment distinction belongs here as well. The E&O section responds to the servicer’s negligent failure to perform an enumerated duty. It does not respond to the collateral loss itself where the servicer performed the duty and the borrower’s hazard carrier simply failed, nor to physical loss on a property the servicer was never obliged to insure. Those are mortgage impairment risks, and a servicer with a significant portfolio of loans in catastrophe exposed markets will carry a mortgage impairment policy alongside the mortgage bankers bond rather than in place of it.
The boundary, then, is coherent. The bond pays when a covered person steals, forges or lies, or when the servicer negligently fails to protect the security it holds for others. It does not pay when the borrower cannot pay, when the market moves, when the regulator fines, or when the insured’s own management chose to look away. A risk program built with that boundary in view will place credit risk with the investor and the mortgage insurer, market risk with the hedge, regulatory risk with the professional liability carrier, and fidelity and servicing errors risk with the mortgage bankers bond, each in its proper place.
Underwriting the Mortgage Banker
The fidelity underwriter does not price a mortgage bankers bond from the limit alone. The limit is the investor’s number; the premium is a function of the insured’s control environment, its funding structure and its servicing book, and the submission that produces a competitive quote is the submission that lets the underwriter see those three things clearly. Surety One’s underwriting review of a mortgage banker concentrates on the following.
- Ownership and management. Who owns the insured, whether any owner or officer has been the subject of investor suspension, FHA Mortgagee Review Board action, state licensing discipline or a prior fidelity claim, and whether the principals’ personal financial condition creates the pressure that precedes owner dishonesty. Because the investor guides require the principal owner to be a covered employee, the principal is underwritten as a fidelity risk in his own right.
- Internal controls over funds. Dual authorization on wires, callback verification of closing instructions and payoff statements against independently sourced contact information, segregation of the people who fund loans from the people who reconcile warehouse and custodial accounts, daily reconciliation of custodial P&I and T&I accounts, and the frequency and independence of the control audit. Funds transfer fraud is now the dominant loss, and the controls over outgoing wires are the dominant rating factor.
- Warehouse facilities. The number of lines, their aggregate capacity, whether funding is wet or dry, the collateral custodian arrangements and the bailee letter mechanics, and the lender’s own collateral audit findings. A lender that has had a collateral exception or a line reduction in the prior twenty four months is a materially different risk.
- Channel mix. The proportion of retail, consumer direct, wholesale broker and correspondent production, because nonemployee origination channels carry forgery and fraudulent documents exposure outside the fidelity agreement and inside the sublimits.
- Quality control. The prefunding and postclosing QC programs the investor guides require, the independence of the QC function from production, the defect rates reported to Fannie Mae and Freddie Mac, the early payment default history and the volume and disposition of repurchase and indemnification demands over the prior three years.
- Servicing portfolio. Owned and subserviced UPB by investor, escrow administration practices, flood zone determination vendor, hazard and flood tracking vendor, force placed insurance practices and tax service arrangements. The E&O half of the bond is priced almost entirely from this data.
- Licensing and approvals. Current NMLS licensure in each state of operation, the state license surety bonds in force, FHA mortgagee approval, VA, USDA and Ginnie Mae issuer status, and the GSE seller/servicer approvals with their most recent eligibility review.
- Financial condition. Audited statements, adjusted net worth against the investor minimums, liquidity, the mix of gain on sale and servicing income, and the trend in both, because a mortgage banker under financial strain is the setting in which both owner dishonesty and servicing neglect occur.
From that review the underwriter structures the bond: the aggregate against the investor formulas, the sub-limits against the actual forgery, closing agent and funds transfer exposures rather than the market’s defaults, the deductible against the net worth ceiling and the insured’s retention appetite, and the endorsement schedule against every warehouse agreement and investor approval the insured holds. The result is a mortgage bankers bond that will be accepted by the investors on its face and will respond when the insured needs it, which are not the same test and are too often treated as if they were.
The Mortgage Bankers Bond Is Not the State License Bond
The word bond invites a confusion that this essay would be incomplete without addressing. Every state that licenses mortgage lenders, mortgage brokers and mortgage loan originators under the SAFE Act framework requires a surety bond as a condition of licensure, filed through the Nationwide Multistate Licensing System (NMLS) and sized by statute or by the licensee’s origination volume. That instrument is a surety bond in the classical sense: a three party contract in which the surety guarantees to the state, as obligee, that the licensee will comply with the licensing statute, with the licensee bound to indemnify the surety for any loss paid. It protects borrowers and the regulator against the licensee’s misconduct; it protects the licensee against nothing. The surety expects no loss and prices the bond as credit, not as risk transfer. The mechanics of that relationship are the subject of The Contractor’s Guide to Surety Bonds and apply to the mortgage license bond as fully as to any other.
The mortgage bankers bond is the opposite instrument in every respect that matters. It is a two party contract of insurance between the mortgage banker and the carrier. It protects the mortgage banker and the parties the mortgage banker designates, not the public. It is required by investors and warehouse lenders rather than by statute. It contemplates loss and is priced to pay it. The fact that the fidelity section carries the vocabulary of the surety industry, bond rather than policy, is a historical artifact of the fidelity and surety companies that wrote the first blanket bonds, and it misleads lenders every year into believing that the license bond they filed with the state satisfies the warehouse lender’s fidelity requirement, or that the mortgage bankers bond they bought from their broker satisfies the state. Neither is true.
A licensed mortgage banker carries both. Surety One writes both, and the state by state requirements for the license bonds are collected in our current practitioner’s guide, Mortgage Industry Surety Bonds, available without charge at constantinpoindexterauthor.com/publications.
The mortgage bankers bond is a composite of three distinct contracts of indemnity that happen to share a declarations page: a blanket fidelity bond descended from the Form 24 and extended to owners, closing agents and investor funds; a set of mortgage specific insuring agreements that address forgery, fraudulent instruments, custodial funds and funds transfer; and a first party mortgagee’s errors and omissions section that insures the lender’s security against its own servicing negligence. Wrapped around the whole is an endorsement schedule that converts warehouse lenders and investors into protected parties and that must be reconciled, at every renewal, against the current text of the Fannie Mae Selling Guide, the Ginnie Mae MBS Guide and the warehouse agreements in force. Each component has its own trigger, its own measure of loss and its own exclusions, and the boundary between all of them and uninsurable credit risk is the loan loss exclusion and the manifest intent standard that the courts have enforced for forty years.
A mortgage banker that understands this structure will buy a better bond, will present itself to its warehouse lenders and investors as a better risk, and will know on the day a loss is discovered which insuring agreement applies and what the proof of loss must show. A fidelity underwriter that understands it will structure and price the bond to the insured’s actual exposures rather than to the investor’s minimum, and will be the counterparty the insured wants on the other end of the claim.
Surety One, Inc. underwrites the mortgage bankers bond for originators, servicers, issuers and correspondents nationwide, together with the state mortgage license surety bonds that accompany it. Underwriting inquiries and submissions may be directed to MortgageBankersBond.com, to Underwriting@SuretyOne.com, or to an underwriter at (919) 859-5294.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- Clore, Duncan L., ed. 2008. Financial Institution Bonds. 3rd ed. Chicago: American Bar Association, Tort Trial and Insurance Practice Section.
- Fannie Mae. 2017a. Selling Guide A3-5-01, Fidelity Bond and Errors and Omissions Coverage Provisions. https://selling-guide.fanniemae.com/sel/a3-5-01/fidelity-bond-and-errors-and-omissions-coverage-provisions
- Fannie Mae. 2017b. Selling Guide A3-5-02, Fidelity Bond Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-02/fidelity-bond-policy-requirements
- Fannie Mae. 2017c. Selling Guide A3-5-03, Errors and Omissions Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-03/errors-and-omissions-policy-requirements
- Fannie Mae. 2017d. Servicing Guide Announcement SVC-2017-07, Fidelity Bond and Errors and Omissions Insurance Requirements. https://singlefamily.fanniemae.com/media/20246/display
- Freddie Mac. 2023. Multifamily Seller/Servicer Guide, Chapter 3, Section 3.16, Seller/Servicer’s Fidelity and Errors & Omissions Insurance Coverage. https://mf.freddiemac.com/docs/chapters/mf_guide_ch_3.pdf
- Freddie Mac. 2024. Become a Freddie Mac Single-Family Seller/Servicer: Document Checklist. https://my.sf.freddiemac.com/docs/pdf/forms/become_ss_customer_document_checklist.pdf
- Ginnie Mae. 2014. Mortgage-Backed Securities Guide, HUD Handbook 5500.3, Rev. 1, Chapter 2, Section 2-7, Fidelity Bond and Errors and Omissions Insurance. https://www.ginniemae.gov/doing_business_with_ginniemae/issuer_resources/MBSGuideLib/Chapter_02.pdf
- Ginnie Mae. 2018. All Participants Memorandum APM 18-06, Fidelity Bond and E&O Insurance Requirements. https://www.ginniemae.gov/memorandum/apm/fidelity-bond-and-eo-insurance-requirements-apm-18-06
- Ginnie Mae. 2024. All Participants Memorandum APM 24-04, Ginnie Mae Central Application for Issuer Insurance and Audited Financial Statements. https://ginniemae.gov/issuers/program_guidelines/Lists/MBSGuideAPMsLib/Attachments/160/APM_24-04.pdf
- Massachusetts Housing Finance Agency. 761 CMR 20.00, Eligibility Guide for Sellers and Servicers. https://www.mass.gov/doc/761-cmr-20-eligibility-guide/download
- Poindexter, C. Constantin. 2025. The Contractor’s Guide to Surety Bonds. Amazon and Barnes & Noble.
- Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000).
- Surety One, Inc. 2026. Mortgage Bankers Bond (Blanket Fidelity Bond). https://suretyone.com/mortgage-bankers-bond-blanket-fidelity-bond
The Mortgage Banker’s Bond: Anatomy of a Hybrid Fidelity and Errors & Omissions Instrument
The mortgage bankers bond is the most misunderstood instrument in the nonbank lender’s risk program, and the misunderstanding is costly. Originators treat it as a compliance checkbox demanded by Fannie Mae, Freddie Mac, Ginnie Mae and the warehouse line, procure the cheapest certificate that satisfies the investor’s declarations page review, and discover only at claim time that the thing they bought is a stratified hybrid of fidelity coverage, first party mortgagee errors and omissions protection, and a set of investor and warehouse lender amendments, each with its own trigger, its own exclusions and its own body of interpretive law. The purpose of this essay is to take the mortgage bankers bond apart, insuring agreement by insuring agreement, and to show how each component maps onto the actual operating exposures of a mortgage banker: the funding of loans with borrowed warehouse money, the custody of escrow and custodial funds, the representations made to secondary market investors, and the servicing obligations that survive the sale of the loan.
The analysis proceeds from the instrument’s lineage in the bankers blanket bond, through the fidelity core and its doctrinal vocabulary (manifest intent, direct loss, discovery), into the mortgage specific insuring agreements that distinguish this form from an ordinary commercial crime policy, and then into the errors and omissions component, which is routinely confused with professional liability insurance and is nothing of the kind. It then examines the warehouse lender and investor amendments, sets out the current coverage mandates of the government sponsored enterprises and Ginnie Mae with their formulas and deductible ceilings, and closes with the exclusions that define the boundary between insurable fidelity and errors risk and uninsurable credit risk. A final section distinguishes the mortgage bankers bond from the state license surety bond with which it shares a name and almost nothing else.
Lineage: From the Bankers Blanket Bond to the Mortgage Bankers Bond
The mortgage bankers bond is a descendant of the bankers blanket bond, the standardized form developed by the Surety Association of America (today the Surety & Fidelity Association of America) for depository institutions and known since its 1986 revision as the Financial Institution Bond, Standard Form No. 24. The blanket bond concept was itself a departure from the individual and schedule fidelity bonds that preceded it: rather than naming the employees covered, the blanket form covered the entire workforce and added a series of non-fidelity insuring agreements (on premises, in transit, forgery or alteration, securities, counterfeit currency) that addressed the ways a financial institution loses money other than through its own people (Clore 2008). The Form 24 vocabulary of insuring agreements lettered A through F, of discovery based coverage, of a single loss definition and a one year discovery period after termination, is the grammar in which every mortgage bankers bond on the market is still written.
The mortgage banking industry is not a depository industry, and the Form 24 did not fit it. A mortgage banker does not hold deposits, rarely handles currency, and faces exposures that no bank form contemplated: forged or fraudulently induced mortgage instruments, failure to record a security instrument, the loss of a note in transit to a custodian, and above all the misapplication of funds that belong to a warehouse lender or a secondary market investor rather than to the insured. In the early 1950s, working with the Mortgage Bankers Association, the fidelity market produced a dedicated mortgage bankers blanket bond that grafted mortgage specific insuring agreements onto the blanket bond chassis and, critically, bolted a mortgagee’s errors and omissions section onto the same policy so that a single instrument could satisfy both the fidelity and the E&O mandates of the investors who purchased the industry’s production.
That dual structure is now written into the investor guides themselves. Fannie Mae’s Selling Guide requires every seller/servicer to carry a blanket fidelity bond and an errors and omissions policy, and for corporate seller/servicers it accepts three fidelity forms by name: the Mortgage Bankers Blanket Bond Policy, the Savings and Loan Blanket Bond Policy, and the Bankers Blanket Bond Policy (Fannie Mae 2017b). Ginnie Mae’s Mortgage-Backed Securities Guide likewise permits an issuer to submit a Mortgage Bankers Bond in lieu of separate fidelity and E&O policies, and warns in the same breath that many products labeled as fidelity or E&O coverage do not in fact meet its requirements (Ginnie Mae 2014). The warning is the point of this essay. The label does not make the coverage; the insuring agreements and the endorsements do.
The Fidelity Core: Employee Dishonesty, Manifest Intent, Direct Loss and Discovery
Insuring Agreement A, fidelity, is the heart of the mortgage bankers bond and the reason the investors require it. It indemnifies the insured for loss resulting directly from dishonest or fraudulent acts of an employee, committed alone or in collusion with others. Three features of that sentence carry the doctrinal weight.
The first is the definition of employee. A bank form covers natural persons in the regular service of the insured. The mortgage bankers bond must reach further, and the investor guides force it to. Fannie Mae requires the fidelity bond to insure against dishonest or fraudulent acts of the seller/servicer’s principal owner, its personnel, employees of outside firms providing legal, data processing or accounting services, and persons supplied by a staffing agency or employed as interns (Fannie Mae 2017b). Ginnie Mae’s enumeration is nearly identical and adds any other person authorized to act on the issuer’s behalf (Ginnie Mae 2014). The inclusion of the principal owner is the single most important divergence from the commercial crime market, where owner dishonesty is universally excluded. A warehouse lender’s greatest fear is not the rogue closer; it is the proprietor who sells the same note twice or diverts the warehouse advance. A mortgage bankers bond that silently carries an owner exclusion, or that fails to carry Ginnie Mae’s required endorsement confirming that principals of a proprietorship or partnership are insured employees, is not compliant coverage however it is labeled.
The second feature is the intent standard. Since the 1986 revision of the Form 24, the fidelity insuring agreement has required that the employee act with the manifest intent to cause the insured to sustain the loss and to obtain a financial benefit for the employee or a third party, with salaries, commissions and ordinary compensation carved out of the definition of benefit; the 2004 revision substituted the phrase improper financial benefit but preserved the architecture (Clore, 2008). The courts have treated manifest intent as something less than a desire to harm the employer but considerably more than reckless disregard of lending standards, and the distinction is decisive in mortgage banking. A loan officer who inflates income on an application to earn a commission on a loan he expects to perform has not, on the prevailing view, manifested an intent to cause the lender a loss; a loan officer who fabricates the borrower and pockets the proceeds has. The leading decisions have insisted that a loss flowing from imprudent or unauthorized loans is a credit loss unless the employee’s purpose was the loss itself (see, for example, Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000)). Modern mortgage bankers bond forms soften this for the industry’s reality by extending fidelity coverage to loan repurchase and indemnification demands that arise from employee dishonesty, but the manifest intent gate remains and the underwriter who understands it will price and structure the bond differently from one who does not.
The third feature is the requirement that loss result directly from the dishonest act. Direct loss excludes the consequential damages that follow a fidelity event in a mortgage shop: the lost gain on sale, the warehouse line that is pulled, the investor that suspends the seller/servicer, the legal fees. It also excludes, through a separate and nearly universal exclusion, loss resulting from the complete or partial nonpayment of or default on any loan, whether or not the loan was procured through fraud, except where the loan loss is itself the product of a covered employee’s dishonesty within Insuring Agreement A. The interplay of the loan exclusion and the fidelity insuring agreement is where most contested mortgage bankers bond claims are fought (Clore, 2008).Finally, the mortgage bankers bond is a discovery form, not a loss sustained form. Coverage attaches to loss discovered during the bond period regardless of when the dishonest act occurred, subject to a prior bond clause, and the insured’s obligations run from discovery: notice within a stated period, sworn proof of loss within a longer period, and automatic termination of coverage as to any employee once the insured learns of that employee’s dishonesty, whether in the insured’s service or elsewhere. Discovery is defined expansively as knowledge of facts that would cause a reasonable person to assume a covered loss has been or will be incurred, even if the amount and details are not yet known. For a mortgage banker, that definition reaches the quality control finding, the investor’s early payment default notice and the warehouse lender’s collateral exception report, each of which may start the notice clock long before anyone has used the word fraud.
The Mortgage Specific Insuring Agreements
What distinguishes a mortgage bankers bond from a bankers blanket bond or a commercial crime policy is the set of insuring agreements and clauses built around the mortgage instrument itself and the parties who touch it between application and sale. The precise lettering and wording vary by market, and the underwriter must read each form, but the exposures they address are constant.
- Forgery or alteration of mortgage instruments. The blanket bond’s forgery agreement was written for checks and drafts. The mortgage bankers bond extends it to promissory notes, mortgages and deeds of trust, assignments, satisfactions and releases, and modification agreements, and the better forms now expressly reach electronically signed and electronically notarized documents. The covered event is the insured’s good faith reliance on an instrument that bears a forged signature or has been materially altered. The loss is measured by the insured’s interest in the instrument, not by the credit quality of the borrower.
- Fraudulent mortgage documents. Closely related but analytically distinct is coverage for loss sustained through the insured’s good faith reliance on a mortgage or note that is genuine on its face but fraudulently procured: the straw buyer, the identity theft refinance, the fictitious property. This clause is the mortgage industry’s answer to the loan exclusion, and it is deliberately narrow. It typically requires that the fraud be in the execution of the instrument or the identity of the mortgagor, not in the borrower’s financial representations, and it is subject to its own sublimit in many forms.
- Failure to record. Negligent failure to record or perfect a security instrument, or to obtain a required lien position, is an errors exposure rather than a dishonesty exposure, and on many forms it sits in the E&O section. Wherever it sits, the loss covered is the impairment of the insured’s or investor’s lien, not the loan balance.
- Closing agent dishonesty. Mortgage bankers fund through settlement agents and closing attorneys who are not employees. The bond extends fidelity style coverage to the theft or misapplication of loan proceeds by the closing agent, which is the exposure that a wet funding warehouse line creates every time a wire leaves the lender before the recorded instrument is in hand.
- Theft of investor or warehouse lender funds and collateral. This is the clause that the warehouse market reads first. It covers the loss of money or collateral belonging to a warehouse lender or secondary market investor, including the original note, while in the insured’s custody, and it is the insuring agreement that the warehouse lender’s additional insured or loss payee endorsement attaches to.
- Custodial and escrow accounts. A servicer holds principal and interest and taxes and insurance funds in custodial accounts that belong to investors and borrowers. The misappropriation of those funds by an employee is fidelity loss under Insuring Agreement A, but the mortgage bankers bond typically names the custodial exposure specifically and confirms that the investor’s interest in the funds is a covered interest.
- Computer systems and funds transfer fraud. Fraudulent instructions that cause the insured, or its warehouse bank, to wire closing funds to an impostor’s account are now the most frequent severity loss in the sector. The coverage grants vary enormously in quality: some forms respond only to unauthorized entry into the insured’s own system, others respond to social engineering that induces an authorized employee to act, and the difference between the two is the difference between a paid claim and a declination.
- Documents in transit. The original note and the collateral file travel between the originator, the document custodian, the warehouse lender’s bailee and the investor. Loss or destruction of those documents in transit, and the cost of reconstitution, is addressed by a transit agreement adapted from the Form 24’s Insuring Agreement C.
Two points of underwriting discipline follow. First, these agreements are frequently sub-limited below the aggregate, and the investor guides measure compliance against the fidelity and E&O limits only; a bond with an adequate aggregate but a $100,000 forgery sublimit may satisfy Fannie Mae and still leave a $3mn funding fraud largely uninsured. Second, the agreements overlap and the bond’s single loss and non-cumulation provisions decide which limit applies when a single scheme implicates several of them. An employee who forges an assignment to divert a warehouse lender’s collateral has committed fidelity loss, forgery loss and theft of collateral in one act, and the bond will pay once.
The Errors and Omissions Component: Mortgagee’s E&O Is Not Professional Liability
The second half of the mortgage bankers bond is routinely misdescribed, by brokers and by lenders alike, as errors and omissions insurance in the sense a lawyer or an accountant would recognize. It is not. Mortgagee’s errors and omissions coverage is a first party property style coverage that indemnifies the mortgagee, and the investors whose interests it carries, for the impairment of the mortgage security caused by the mortgagee’s own negligent failure to perform specific servicing duties. It does not defend the lender against a borrower’s lawsuit, it does not respond to a regulatory investigation, and it does not pay a third party’s damages. Those exposures belong to a separate mortgage bankers professional liability policy, which is a claims made liability contract with a duty to defend and which no investor guide requires.
The servicing duties that mortgagee’s E&O insures are enumerated in the investor guides and have been stable for decades. Fannie Mae requires that the policy protect the seller/servicer at least against negligence, errors and omissions in maintaining property and flood insurance on the collateral, maintaining required mortgage insurance or loan guaranty, determining whether a property lies in a Special Flood Hazard Area, paying real estate taxes and special assessments, and complying with the reporting requirements of the mortgage insurer or guarantor (Fannie Mae 2017c). Ginnie Mae’s list is the same in substance, framed around FHA insurance and VA, RD and PIH guaranties and around the issuer’s duty to keep the mortgaged property insured in accordance with the MBS Guide (Ginnie Mae 2014). The classic mortgagee’s E&O form expresses these as separate insuring agreements: hazard insurance, flood insurance, real estate tax, mortgage guaranty insurance, life and disability insurance on the mortgagor where the mortgage requires it, and loss of or damage to the mortgagee’s interest in the property or documents.
The loss paid under each agreement is the mortgagee’s actual loss of security. If a servicer allows the hazard policy to lapse and the house burns, the E&O agreement pays what the hazard carrier would have paid, less the deductible, to the extent of the mortgagee’s interest. If the servicer fails to pay the taxes and the county’s tax deed extinguishes the lien, the agreement pays the lien that was lost. If the servicer fails to maintain the FHA insurance and the loan defaults, the agreement pays the claim HUD would have paid. This is why Fannie Mae will accept a mortgage impairment or mortgagee interest policy in substitution for a stand alone E&O policy provided it delivers substantially the same coverage (Fannie Mae 2017c): the two products insure the same interest by different mechanisms. Mortgage impairment insurance is written on a per loan basis and responds to physical loss to the collateral when the servicer’s required insurance has failed; mortgagee’s E&O is written on an aggregate basis and responds to the servicer’s negligent act, whatever the collateral’s fate.
The practical consequences for the mortgage banker are three. First, because the E&O section pays the mortgagee’s loss of security and not a liability judgment, its limit need not and should not be sized to litigation exposure; the investor guides tie it to the fidelity limit for a reason. Second, because the covered duties are servicing duties, an originator that sells servicing released and retains no portfolio has a materially smaller E&O exposure than a servicer with a $2bn book of escrowed loans, and the underwriter will price accordingly even though the investor’s minimum limit is the same. Third, because the E&O section is first party, the investor’s rights under it are rights to the proceeds, which is why the loss payee and direct claim provisions discussed below reach both halves of the bond.
Warehouse Lender and Investor Amendments
A mortgage banker funds with other people’s money. The warehouse lender advances the closing funds against a security interest in the note and mortgage, takes delivery of the original note under a bailee letter or through a document custodian, and is repaid when the loan is sold to the investor, typically within thirty to sixty days. During that interval the warehouse lender’s collateral is a piece of paper in the originator’s or custodian’s possession, and the originator’s employees and principals control the flow of funds in and out. The warehouse lender therefore underwrites the originator’s fidelity program as carefully as it underwrites the originator’s balance sheet, and it conditions the line on amendments to the mortgage bankers bond that convert the lender from a stranger to the contract into a protected party.
The amendments are of four kinds, and the underwriter who writes mortgage bankers bonds must be fluent in each.
- Additional insured or joint loss payee status. The warehouse lender, and often each investor with which the originator has a purchase agreement, is named by endorsement so that the lender’s loss of money or collateral through the originator’s employee dishonesty, forgery or theft is a covered loss and the proceeds are payable to the lender as its interest appears. Fannie Mae reserves the same rights for itself in the policy provisions it requires (Fannie Mae 2017a). The drafting matters: a bare loss payee clause gives the lender a right to proceeds the insured has already established; an additional insured clause gives the lender its own claim.
- Direct claim and direct payment. Ginnie Mae requires that it have the right to file a claim directly with the insurer and be paid directly by the insurer, and that it be named on the loss draft where its interest is affected (Ginnie Mae 2014). Sophisticated warehouse lenders negotiate the same right, so that the originator’s insolvency or indifference does not stand between the lender and the bond.
- Notice of cancellation, reduction and restrictive modification. The warehouse lender’s protection is only as good as its knowledge that the bond is in force. The endorsement obligates the insurer to give the lender advance written notice, thirty days being the industry convention and the term Surety One’s own program literature has long described for Fannie Mae, before the bond is cancelled, the aggregate is reduced other than by payment of loss, or coverage is restricted (Surety One 2026). Fannie Mae’s policy provisions and reporting requirements track the same concept, requiring the seller/servicer to notify it of cancellation, reduction, nonrenewal or restrictive modification (Fannie Mae 2017a; Fannie Mae 2017d), and Ginnie Mae requires that it be notified whether the change is for cause or at the issuer’s request (Ginnie Mae 2014).
- Owner and principal dishonesty. As discussed above, the investor guides require the principal owner to be a covered employee. The warehouse lender’s endorsement usually goes a step further and confirms that the lender’s recovery is not defeated by the fact that the dishonest actor controlled the insured, which is precisely the double pledging and double selling scenario the lender fears most. A mortgage bankers bond that excludes loss caused by any owner or partner, or that conditions coverage on the dishonesty being unknown to management, offers the warehouse lender nothing in the case that matters.
Two further structural points deserve notice. The first is that the warehouse lender’s protection under the originator’s bond is derivative: it is limited by the originator’s aggregate, eroded by the originator’s other losses, and subject to the originator’s compliance with the notice and proof of loss conditions. Warehouse lenders with large correspondent networks therefore buy their own mortgage investor bond, a distinct instrument that treats the employees of approved correspondents as employees of the warehouse lender and carries a fraudulent mortgage clause written from the purchaser’s side. The second is that the warehouse lender’s endorsement and the investor’s required provisions are not interchangeable, and the mortgage banker that carries three warehouse lines and sells to five investors will carry an endorsement schedule that must be reconciled at every renewal. That reconciliation is underwriting work, and it is the service a specialist underwriter provides that a certificate mill does not.
Investor Mandates: Fannie Mae, Freddie Mac and Ginnie Mae
The limits on a mortgage bankers bond are not chosen; they are computed. Each of the three principal secondary market counterparties publishes a formula, a cap and a deductible ceiling, and the bond must satisfy the most demanding of the formulas that apply to the insured’s approvals.
Fannie Mae’s requirements, consolidated into the Selling Guide in 2017 after nearly two decades without material revision, measure the required fidelity coverage against the greater of the seller/servicer’s annual total unpaid principal balance of single family and multifamily originations or its highest monthly total UPB of loans it owns and services, including loans it owns that are subserviced by others (Fannie Mae 2017b). The schedule is cumulative:
- Total UPB of $100mn or less: $300,000.
- Over $100mn up to $1bn: $300,000 plus 0.150 percent of the next $400mn plus 0.125 percent of the next $500mn.
- Over $1bn: the foregoing plus 0.100 percent of the amount over $1bn.
- Maximum required fidelity coverage: $150mn.
The maximum deductible for seller/servicers with UPB of $1bn or less is the higher of 10 percent of the face amount or $100,000; above $1bn it is 15 percent, with a larger deductible available only on Fannie Mae’s prior written consent and in no event exceeding 1 percent of the seller/servicer’s net worth (Fannie Mae 2017b). The errors and omissions coverage must equal the fidelity coverage so computed, but Fannie Mae does not require E&O above $10mn for a single family only seller/servicer or $30mn for one that sells or services both single family and multifamily loans; per loan E&O policies are accepted if the insurer’s liability per loan at least equals the highest UPB of any loan the seller/servicer owns, with a per loan deductible no greater than 5 percent, and aggregate E&O deductibles follow the same 10 percent or $100,000 and 15 percent schedule as the fidelity bond (Fannie Mae 2017c). A subsidiary may rely on its parent’s bond if it is a joint insured, Lloyd’s affiliated coverage is acceptable, and the seller/servicer must report any single fidelity or E&O loss that is mortgage related within 30 days of discovery (Fannie Mae 2017a; Fannie Mae 2017d).
Ginnie Mae’s requirements, in Chapter 2 of the Mortgage-Backed Securities Guide (HUD Handbook 5500.3, Rev. 1), begin from a $300,000 minimum for both the fidelity bond and the mortgagee’s E&O policy, written either per loss or in the aggregate, and scale with the issuer’s total servicing portfolio, including Fannie Mae, Freddie Mac, private label and portfolio loans: 0.15 percent of the portfolio between $100mn and $500mn, 0.125 percent between $500mn and $1bn, and 0.1 percent above $1bn, so that a $500mn portfolio requires $900,000, a $1bn portfolio $1.525mn, and a $1.5bn portfolio $2.025mn (Ginnie Mae 2014). Ginnie Mae historically capped the E&O requirement at $20mn and permits a fidelity cap below the formula where the issuer demonstrates that the government sponsored enterprises have capped its coverage (Ginnie Mae 2014). In 2018 Ginnie Mae realigned its coverage and deductible standards with the enterprise schedule for policies and renewals on and after January 1, 2019, eliminated its separate loss payable endorsement requirement as redundant of its direct claim and direct payment rights, and began requiring issuers to upload the complete bond and E&O policy, not merely certificates, through its issuer portal (Ginnie Mae 2018); the 2024 revisions moved that submission to Ginnie Mae Central and made the full policy with all endorsements the standard evidence of coverage at every renewal (Ginnie Mae 2024). The carrier must be rated B+ or better by A.M. Best and licensed or authorized where the collateral properties lie (Ginnie Mae 2014).
Freddie Mac’s single family requirements parallel Fannie Mae’s in structure and are enforced at the point of approval, where the applicant must deliver the declarations pages of both its fidelity bond and its errors and omissions policy together with its warehouse agreements (Freddie Mac 2024); its Multifamily Seller/Servicer Guide carries a dedicated section on fidelity and E&O coverage with its own notice obligations (Freddie Mac 2023). State housing finance agencies that purchase or master service loans impose comparable formulas, Massachusetts being a published example that ties fidelity coverage to a percentage of the servicing portfolio and sets a $1mn E&O floor (MassHousing 761 CMR 20).
The operational lesson is that the limit must be recomputed at every renewal against the originator’s trailing twelve month production and its month end owned servicing peak, that the deductible must be tested against both the percentage ceiling and the net worth ceiling, and that the endorsements must be refreshed against the current text of each guide. A bond that was compliant when bound can fall out of compliance in a single strong quarter of originations.
Exclusions and the Credit Risk Boundary
Every fidelity instrument draws a line between the risk the surety will carry and the risk that belongs to the insured’s own business judgment, and in the mortgage bankers bond that line separates fidelity and errors risk from credit risk. The exclusions that enforce it are not boilerplate; they are the negotiated perimeter of the product, and the mortgage banker that understands them will structure its operations so that its real exposures fall inside the perimeter rather than outside it.
- The loan loss exclusion. Loss resulting from the complete or partial nonpayment of or default on any loan or extension of credit is excluded, whether the loan was procured in good faith or through trick, artifice, fraud or false pretenses, except to the extent the loss is covered under the fidelity agreement, the forgery agreement or the fraudulent mortgage documents clause. The exclusion is the single most litigated provision in financial institution bond law, and the courts have generally enforced it against lenders who attempt to recast underwriting failures as fraud (Clore 2008). The mortgage bankers bond’s fraudulent documents clause is the industry’s negotiated carve back, and its scope defines how much origination fraud is actually insured.
- Indirect and consequential loss. Loss of income, loss of potential income including interest and dividends not realized, damages for which the insured is liable to third parties except as specifically covered, and costs, fees and expenses incurred in establishing the existence or amount of a loss are excluded. The repurchase demand that follows an investor’s discovery of a fraudulent loan is a liability of the insured to a third party, which is why the modern forms’ express extension of fidelity coverage to repurchase and indemnification loss arising from employee dishonesty is a material enhancement and not a drafting nicety.
- Prior knowledge and the termination as to employee clause. The bond does not cover loss caused by an employee after the insured has learned of any dishonest act committed by that employee, at any time, in the insured’s service or elsewhere. A mortgage banker that rehires a loan officer dismissed by a competitor for application fraud has, in most forms, uninsured that loan officer from the day of hire. The same principle applies to a principal whose prior dishonesty was known to the other owners.
- Trading, market and valuation loss. Loss resulting from the fluctuation in the market value of loans or servicing rights, from hedging activity, from the exercise of secondary marketing judgment, or from the movement of interest rates is excluded, because it is the business of the mortgage banker and not a fidelity event.
- Fines, penalties and regulatory loss. Civil money penalties, consumer restitution ordered by a regulator, and the cost of responding to an examination are excluded from the bond and are the province of professional liability and regulatory coverage, if insured at all.
- Nonemployee and nonauthorized actors. Loss caused by a borrower, a broker, a correspondent or an appraiser acting alone is not fidelity loss; it is covered, if at all, only through the forgery, fraudulent documents or closing agent agreements and their sublimits. The mortgage banker that sources production through a third party origination channel carries a structurally different exposure from the retail lender, and the underwriter will examine the channel mix for exactly that reason.
The mortgage impairment distinction belongs here as well. The E&O section responds to the servicer’s negligent failure to perform an enumerated duty. It does not respond to the collateral loss itself where the servicer performed the duty and the borrower’s hazard carrier simply failed, nor to physical loss on a property the servicer was never obliged to insure. Those are mortgage impairment risks, and a servicer with a significant portfolio of loans in catastrophe exposed markets will carry a mortgage impairment policy alongside the mortgage bankers bond rather than in place of it.
The boundary, then, is coherent. The bond pays when a covered person steals, forges or lies, or when the servicer negligently fails to protect the security it holds for others. It does not pay when the borrower cannot pay, when the market moves, when the regulator fines, or when the insured’s own management chose to look away. A risk program built with that boundary in view will place credit risk with the investor and the mortgage insurer, market risk with the hedge, regulatory risk with the professional liability carrier, and fidelity and servicing errors risk with the mortgage bankers bond, each in its proper place.
Underwriting the Mortgage Banker
The fidelity underwriter does not price a mortgage bankers bond from the limit alone. The limit is the investor’s number; the premium is a function of the insured’s control environment, its funding structure and its servicing book, and the submission that produces a competitive quote is the submission that lets the underwriter see those three things clearly. Surety One’s underwriting review of a mortgage banker concentrates on the following.
- Ownership and management. Who owns the insured, whether any owner or officer has been the subject of investor suspension, FHA Mortgagee Review Board action, state licensing discipline or a prior fidelity claim, and whether the principals’ personal financial condition creates the pressure that precedes owner dishonesty. Because the investor guides require the principal owner to be a covered employee, the principal is underwritten as a fidelity risk in his own right.
- Internal controls over funds. Dual authorization on wires, callback verification of closing instructions and payoff statements against independently sourced contact information, segregation of the people who fund loans from the people who reconcile warehouse and custodial accounts, daily reconciliation of custodial P&I and T&I accounts, and the frequency and independence of the control audit. Funds transfer fraud is now the dominant loss, and the controls over outgoing wires are the dominant rating factor.
- Warehouse facilities. The number of lines, their aggregate capacity, whether funding is wet or dry, the collateral custodian arrangements and the bailee letter mechanics, and the lender’s own collateral audit findings. A lender that has had a collateral exception or a line reduction in the prior twenty four months is a materially different risk.
- Channel mix. The proportion of retail, consumer direct, wholesale broker and correspondent production, because nonemployee origination channels carry forgery and fraudulent documents exposure outside the fidelity agreement and inside the sublimits.
- Quality control. The prefunding and postclosing QC programs the investor guides require, the independence of the QC function from production, the defect rates reported to Fannie Mae and Freddie Mac, the early payment default history and the volume and disposition of repurchase and indemnification demands over the prior three years.
- Servicing portfolio. Owned and subserviced UPB by investor, escrow administration practices, flood zone determination vendor, hazard and flood tracking vendor, force placed insurance practices and tax service arrangements. The E&O half of the bond is priced almost entirely from this data.
- Licensing and approvals. Current NMLS licensure in each state of operation, the state license surety bonds in force, FHA mortgagee approval, VA, USDA and Ginnie Mae issuer status, and the GSE seller/servicer approvals with their most recent eligibility review.
- Financial condition. Audited statements, adjusted net worth against the investor minimums, liquidity, the mix of gain on sale and servicing income, and the trend in both, because a mortgage banker under financial strain is the setting in which both owner dishonesty and servicing neglect occur.
From that review the underwriter structures the bond: the aggregate against the investor formulas, the sub-limits against the actual forgery, closing agent and funds transfer exposures rather than the market’s defaults, the deductible against the net worth ceiling and the insured’s retention appetite, and the endorsement schedule against every warehouse agreement and investor approval the insured holds. The result is a mortgage bankers bond that will be accepted by the investors on its face and will respond when the insured needs it, which are not the same test and are too often treated as if they were.
The Mortgage Bankers Bond Is Not the State License Bond
The word bond invites a confusion that this essay would be incomplete without addressing. Every state that licenses mortgage lenders, mortgage brokers and mortgage loan originators under the SAFE Act framework requires a surety bond as a condition of licensure, filed through the Nationwide Multistate Licensing System (NMLS) and sized by statute or by the licensee’s origination volume. That instrument is a surety bond in the classical sense: a three party contract in which the surety guarantees to the state, as obligee, that the licensee will comply with the licensing statute, with the licensee bound to indemnify the surety for any loss paid. It protects borrowers and the regulator against the licensee’s misconduct; it protects the licensee against nothing. The surety expects no loss and prices the bond as credit, not as risk transfer. The mechanics of that relationship are the subject of The Contractor’s Guide to Surety Bonds and apply to the mortgage license bond as fully as to any other.
The mortgage bankers bond is the opposite instrument in every respect that matters. It is a two party contract of insurance between the mortgage banker and the carrier. It protects the mortgage banker and the parties the mortgage banker designates, not the public. It is required by investors and warehouse lenders rather than by statute. It contemplates loss and is priced to pay it. The fact that the fidelity section carries the vocabulary of the surety industry, bond rather than policy, is a historical artifact of the fidelity and surety companies that wrote the first blanket bonds, and it misleads lenders every year into believing that the license bond they filed with the state satisfies the warehouse lender’s fidelity requirement, or that the mortgage bankers bond they bought from their broker satisfies the state. Neither is true.
A licensed mortgage banker carries both. Surety One writes both, and the state by state requirements for the license bonds are collected in our current practitioner’s guide, Mortgage Industry Surety Bonds, available without charge at constantinpoindexterauthor.com/publications.
The mortgage bankers bond is a composite of three distinct contracts of indemnity that happen to share a declarations page: a blanket fidelity bond descended from the Form 24 and extended to owners, closing agents and investor funds; a set of mortgage specific insuring agreements that address forgery, fraudulent instruments, custodial funds and funds transfer; and a first party mortgagee’s errors and omissions section that insures the lender’s security against its own servicing negligence. Wrapped around the whole is an endorsement schedule that converts warehouse lenders and investors into protected parties and that must be reconciled, at every renewal, against the current text of the Fannie Mae Selling Guide, the Ginnie Mae MBS Guide and the warehouse agreements in force. Each component has its own trigger, its own measure of loss and its own exclusions, and the boundary between all of them and uninsurable credit risk is the loan loss exclusion and the manifest intent standard that the courts have enforced for forty years.
A mortgage banker that understands this structure will buy a better bond, will present itself to its warehouse lenders and investors as a better risk, and will know on the day a loss is discovered which insuring agreement applies and what the proof of loss must show. A fidelity underwriter that understands it will structure and price the bond to the insured’s actual exposures rather than to the investor’s minimum, and will be the counterparty the insured wants on the other end of the claim.
Surety One, Inc. underwrites the mortgage bankers bond for originators, servicers, issuers and correspondents nationwide, together with the state mortgage license surety bonds that accompany it. Underwriting inquiries and submissions may be directed to MortgageBankersBond.com, to Underwriting@SuretyOne.com, or to an underwriter at (919) 859-5294.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- Clore, Duncan L., ed. 2008. Financial Institution Bonds. 3rd ed. Chicago: American Bar Association, Tort Trial and Insurance Practice Section.
- Fannie Mae. 2017a. Selling Guide A3-5-01, Fidelity Bond and Errors and Omissions Coverage Provisions. https://selling-guide.fanniemae.com/sel/a3-5-01/fidelity-bond-and-errors-and-omissions-coverage-provisions
- Fannie Mae. 2017b. Selling Guide A3-5-02, Fidelity Bond Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-02/fidelity-bond-policy-requirements
- Fannie Mae. 2017c. Selling Guide A3-5-03, Errors and Omissions Policy Requirements. https://selling-guide.fanniemae.com/sel/a3-5-03/errors-and-omissions-policy-requirements
- Fannie Mae. 2017d. Servicing Guide Announcement SVC-2017-07, Fidelity Bond and Errors and Omissions Insurance Requirements. https://singlefamily.fanniemae.com/media/20246/display
- Freddie Mac. 2023. Multifamily Seller/Servicer Guide, Chapter 3, Section 3.16, Seller/Servicer’s Fidelity and Errors & Omissions Insurance Coverage. https://mf.freddiemac.com/docs/chapters/mf_guide_ch_3.pdf
- Freddie Mac. 2024. Become a Freddie Mac Single-Family Seller/Servicer: Document Checklist. https://my.sf.freddiemac.com/docs/pdf/forms/become_ss_customer_document_checklist.pdf
- Ginnie Mae. 2014. Mortgage-Backed Securities Guide, HUD Handbook 5500.3, Rev. 1, Chapter 2, Section 2-7, Fidelity Bond and Errors and Omissions Insurance. https://www.ginniemae.gov/doing_business_with_ginniemae/issuer_resources/MBSGuideLib/Chapter_02.pdf
- Ginnie Mae. 2018. All Participants Memorandum APM 18-06, Fidelity Bond and E&O Insurance Requirements. https://www.ginniemae.gov/memorandum/apm/fidelity-bond-and-eo-insurance-requirements-apm-18-06
- Ginnie Mae. 2024. All Participants Memorandum APM 24-04, Ginnie Mae Central Application for Issuer Insurance and Audited Financial Statements. https://ginniemae.gov/issuers/program_guidelines/Lists/MBSGuideAPMsLib/Attachments/160/APM_24-04.pdf
- Massachusetts Housing Finance Agency. 761 CMR 20.00, Eligibility Guide for Sellers and Servicers. https://www.mass.gov/doc/761-cmr-20-eligibility-guide/download
- Poindexter, C. Constantin. 2025. The Contractor’s Guide to Surety Bonds. Amazon and Barnes & Noble.
- Resolution Trust Corp. v. Fidelity & Deposit Co. of Maryland, 205 F.3d 615 (3d Cir. 2000).
- Surety One, Inc. 2026. Mortgage Bankers Bond (Blanket Fidelity Bond). https://suretyone.com/mortgage-bankers-bond-blanket-fidelity-bond