The Quiet Franchise: Commercial Surety as a Safe Haven for the Specialist Carrier
A franchise that does not make headlines
Contract surety gets the attention. It carries the nine figure bond limits, the megaproject defaults and the reinsurance disputes that follow them, and it is where the industry’s loss ratio is made or lost in any given year. Commercial surety, the license and permit, court, fiduciary, public official, customs and miscellaneous obligations that regulators and courts require of businesses and individuals, is the part of the business nobody writes about, . . . or, at least DIDN’T write about. I remember when we still called them “nuisance bonds”. It is also, for a carrier that has chosen to specialize in surety rather than treat it as a line among forty, the closest thing the P&C industry offers to a safe haven.
The term needs defining or it is marketing. A safe haven, in the sense used here, is a book whose demand does not move with the construction cycle, whose severity is bounded by instrument rather than by circumstance, whose losses are recoverable from the principal by contract, and whose underwriting can be conducted by a disciplined specialist at an expense ratio a multiline carrier cannot match. Commercial surety meets each of those tests, and the evidence for the proposition is not anecdotal. It is in the statutory results, in the academic literature on insurer specialization, and in the one period in modern memory when the haven failed, which happened for reasons that are entirely avoidable.
Why the structure of the obligation matters
Four features distinguish a commercial surety book from a contract book, and together they explain why the former behaves as a haven.
Demand is statutory and inelastic. A contractor buys a performance bond because an owner awarded a contract; when awards fall, so does premium. A motor vehicle dealer, a freight broker, a mortgage originator, an executor, an appellant or an importer buys a bond because a statute, a court order or a federal regulation requires it as a condition of doing business at all. The bond is renewed whether the economy expands or contracts, and in a downturn the regulated population shrinks far less than construction starts do. Commercial surety trends, including license, permit and court bonds, remained stable at mid-year 2026 while contract writers were absorbing megaproject concentration and input cost inflation (Baldwin Group 2026).
Severity is bounded by the instrument. For commercial surety and court bonds, loss is generally capped at the penal sum; for contract surety the penalty does not reliably cap economic loss, because completion cost after a takeover, reletting at higher prices and defective workmanship liability can all pierce it (hyperexponential 2026). A commercial underwriter knows the worst case the day the bond is written. A contract underwriter learns it when the replacement contractor’s bid comes in.
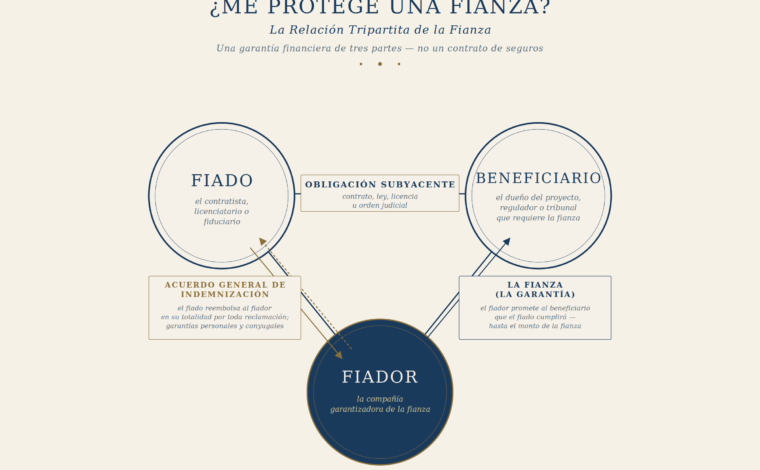
Losses are recoverable by contract. Every bond of consequence is written against a general agreement of indemnity, and the expectation that the surety will recover paid losses from the principal materially reduces net expected loss, which is why surety direct loss ratios run lower than other commercial casualty lines to begin with (hyperexponential 2026). In commercial surety the principal is typically an operating business or an individual with assets, collateral is routinely taken on larger obligations, and the bond is cancellable on notice, so the surety can exit a deteriorating credit rather than ride it to default.
Underwriting scales. License and permit bonds are underwritten on credit score and financial data with little human judgment per unit, which rewards the carrier that has built the process and penalizes the one that treats each $25,000 bond as a file. The specialist’s advantage is not that it knows something the multiline does not. It is that the specialist’s entire cost structure is built around doing this one thing cheaply and well.
What the results say
Surety as a whole is the most profitable major commercial line in the United States. Surety writers produced net profit margins above 30 percent in every year from 2014 through 2024, outperforming every other major commercial line over the period, and the direct incurred loss ratio fell more than four points through the third quarter of 2025 against the prior year (AM Best 2026). NAIC market share data put the 2024 direct loss ratio for surety at 23.49 percent, against 77.63 percent for commercial auto liability and 70.77 percent for general liability (NAIC 2025). Guy Carpenter’s analysis of statutory data found an industry combined ratio of roughly 71 percent over the five years to 2022 (Guy Carpenter 2023).
Those industry figures blend a volatile contract book with a stable commercial one, and the blend flatters the former. The clearest public signal of the difference is the behavior of the two segments when losses rise. When the industry direct loss ratio climbed from 15.0 percent in 2022 to 21.0 percent at third quarter 2023, the deterioration was a contract phenomenon; commercial surety remained profitable, claim activity was described as picking up but losses as remaining low, and the segment continued to attract new entrants, both direct writers and managing general agents (WTW 2024). Surety reinsurance results were more dramatic over the same period because reinsurers sit above the contract retentions where the severity lands (WTW 2024). The SFAA’s statistical plan reports, which break results down by class code, are available to members and tell the same story in detail: license and permit bonds run favorably because frequency is low and severity is capped, and contract surety is the most cyclical of the three sub lines (hyperexponential 2026).
The specialist premium shows up at the company level. Merchants Bonding Company, which has focused almost exclusively on surety for nearly a century, has carried an A or better rating from AM Best since 1958 and in one recent quarter posted a 1.3 percent direct loss ratio against an industry figure of 22.3 percent (Merchants Bonding 2024). Guy Carpenter’s segmentation of the market found the top five writers running a five year direct combined ratio of 66 percent against 77 percent for the next fifteen, with the gap attributed to access to stronger credits and to tiered commission structures on larger bonds (Guy Carpenter 2023). A commercial surety specialist competes on the opposite end of that curve: not by writing the largest bonds, but by writing the most bonds at the lowest marginal cost.
What the literature says about specialists
The intuition that a focused carrier outperforms a diversified one is not merely an industry prejudice. Liebenberg and Sommer (2008), using a sample of property and liability insurers from 1995 through 2004, tested the conglomeration hypothesis, under which diversification should improve performance through risk pooling and internal capital markets, against the strategic focus hypothesis, under which diversification exacerbates agency costs and cross subsidizes weak lines. They found that undiversified insurers consistently outperform diversified ones, with a diversification penalty of at least one percent of return on assets or two percent of return on equity, and that the market applies a significant discount to diversified insurers measured by Tobin’s Q. The result was robust to corrections for endogeneity and alternative measures of risk and diversification, and the authors read it as strong support for the strategic focus hypothesis. A later study by the same group found that the extent of diversification is not driven by risk pooling considerations at all; insurers operating in more volatile lines do not diversify more, which undercuts the main theoretical defense of the multiline model (Berry-Stölzle et al. 2012).
Applied to surety, the finding has a specific mechanism. In a multiline carrier the surety department competes for capital and attention with lines that produce ten times its premium, its underwriters are evaluated against a group combined ratio they cannot move, and its appetite is set by a committee that may not be able to tell a court bond from a completion bond. When losses appear anywhere in the group, surety capacity is the first thing cut because it is the easiest thing to explain. The specialist faces none of that. Its capital is dedicated, its reinsurance is purchased for this book and this book only, and its decision to write or decline a class is made by people who will be there when the bond matures. That is the strategic focus premium in operation, and commercial surety, with its high volume and low severity, is the segment where it compounds fastest.
The present cycle is proving the point
The current environment is a natural experiment. On the contract side, 2026 brings megaproject concentration, data center bond limits riding on a handful of specialty electrical contractors behind special purpose vehicles, a Coface forecast of an 8 percent rise in United States insolvencies with construction among the named sectors, and a reinsurance market that intends to differentiate hard by cedent at 1/1 2027 (Willis Re 2026; Coface 2026). Every one of those pressures lands on the contract book.
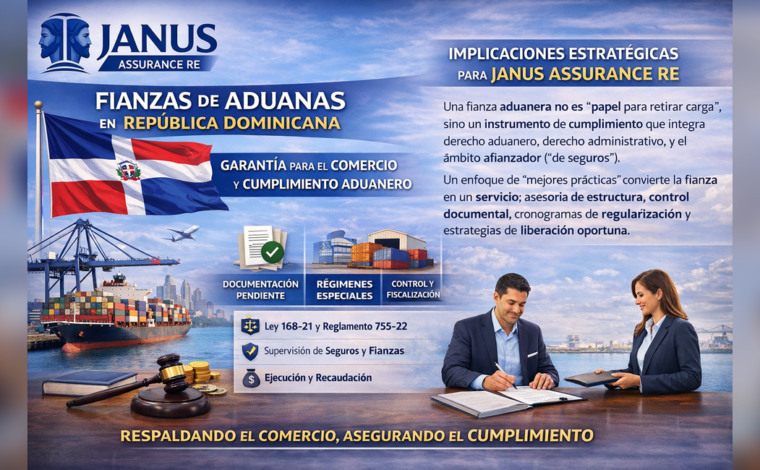
The same macro forces are expanding commercial surety demand. Customs bonds are the sharpest example. Because a continuous importer bond must be set at not less than ten percent of the prior year’s duties, taxes and fees, tariff increases raise required bond amounts mechanically even where shipment volumes are flat (Foley & Lardner 2026). Customs and Border Protection identified 27,479 bond insufficiencies in fiscal 2025 worth nearly $3.6bn, double the 2019 level, with importers now facing bond amounts from the $50,000 minimum to as high as $450mn (CNBC 2026). CBP collected $30bn in tariffs in January 2026 alone, and every dollar of it flows into the sufficiency formula. Regulatory expansion does the same work more slowly: each new licensing regime, each increase in a statutory bond threshold, each court that requires security on appeal adds obligors who have no choice but to buy.
The result is a segment whose premium grows when the economy is stressed, whose losses stay bounded when contract losses do not, and whose principals are screened by the state before the surety ever sees them. A specialist that has built its book here is not insulated from the cycle. It is positioned on the side of the cycle where the cash flows in.
Where the haven ends
My point here does have a condition, and the industry learned it the expensive way. Between 2000 and 2002 insurers reported almost $1bn in direct losses from commercial surety bonds alone, the bulk of it from a single class of obligation: bonds written on Enron’s prepaid natural gas and oil forward contracts with Mahonia, a special purpose vehicle controlled by J.P. Morgan Chase (CFO 2002). When Enron failed, Chase demanded $965mn under the bonds; the eleven sureties refused, arguing that the forward sales were disguised loans and that a surety may not lawfully guarantee a loan; and in January 2003 the parties settled for approximately $654mn, with Travelers alone paying roughly $160mn (J.P. Morgan Chase 2003; Business Insurance 2003). An internal Kemper underwriting memo produced in the litigation had described the Enron bonds, approvingly, as long tail financial guarantees (CFO 2003).
That episode is the whole lesson in one sentence. Commercial surety is a haven only so long as the obligation it secures is a performance or compliance obligation of a going concern, bounded in amount, cancellable in term and recoverable from an indemnitor. The moment the product is stretched to guarantee a counterparty’s payment on a financial contract, it stops being surety and becomes credit enhancement with surety’s pricing, and the penal sum is no longer a ceiling on loss but a target for a sophisticated obligee. AM Best’s rating methodology draws the same line: commercial portfolios with several large potential loss exposures are evaluated like contract books, by estimating a potential large net loss on each, and only genuinely granular portfolios are analyzed in the aggregate (AM Best 2017). The one surplus lines impairment of the past two decades was a monoline surety writing bonds on private student loans (AM Best 2025). The haven does not protect the carrier that leaves it.
The discipline is therefore not complicated, but it must be absolute. No financial guarantees under any name. No bond whose penal sum exceeds what the surety would lend the principal unsecured. No concentration in a single class of regulated obligor whose regulator can change the rules, as the fuel tax and reclamation bond writers learned. And no acceptance of an obligee’s form that converts a conditional undertaking into an absolute one. A specialist that holds those lines has a franchise that will outlast the next contract cycle. One that does not has merely found a slower way to write a performance bond.
The quiet franchise
The surety industry has spent a decade congratulating itself on contract results that infrastructure spending delivered and that reinsurers are now being asked to pay for. The commercial surety book earned its returns differently: bond by bond, renewal by renewal, on obligors the state compelled to buy and on obligations whose worst case was printed on the face of the instrument. It will go on earning them when the data center cycle turns, because the dealers, brokers, fiduciaries and importers who make up the book will still need their bonds, and the carrier that has spent twenty years learning how to write them for a few basis points of expense will still be the one they call.
That is what a safe haven looks like in this business. Not a product that cannot lose, but one whose losses are bounded, whose demand is legislated, and whose economics reward the carrier willing to be boring for a very long time. Yes, doing all of those nuisance bonds. Know what the franchise is worth and know where it ends. Janus Assurance Re reinsures commercial surety specialists for exactly that reason, and Surety One, Inc., its managing general agent for the western hemisphere, has written the class across the United States, Puerto Rico and the Caribbean for more than three decades.
Janus Assurance Re is a Dominican domiciled reinsurer of surety, fidelity and credit risks. Surety One, Inc. is its exclusive managing general agent for the western hemisphere.
~ C. Constantin Poindexter, MA, JD, CPCU, AFSB, ASLI, ARe, AINS, AIS, CPLP
References
- AM Best. 2017. Rating Surety Companies. Best’s Credit Rating Methodology criteria procedure, October 13. https://www3.ambest.com/ambv/ratingmethodology/openpdf.aspx?ubcr=1&ri=1273.
- AM Best. 2025. Market Segment Report: The Need for Specialized Expertise Propels the US Surplus Lines Market. September 9. https://web.ambest.com/docs/default-source/events/market-segment-report—the-need-for-specialized-expertise-propels-the-us-surplus-lines-market.pdf.
- AM Best. 2026. “Best’s Special Report: Infrastructure Projects Spur Growth and Help Fuel Profits for U.S. Surety Insurers.” Press release, January 19. https://news.ambest.com/PR/PressContent.aspx?altsrc=2&refnum=36948.
- Baldwin Group. 2026. “2026 Surety and SDI Mid-Year State of the Market.” https://baldwin.com/insights/surety-industry-report/.
- Berry-Stölzle, Thomas R., Andre P. Liebenberg, Joseph Ruhland, and David W. Sommer. 2012. “Determinants of Corporate Diversification: Evidence from the Property–Liability Insurance Industry.” Journal of Risk and Insurance 79 (2): 381–413. https://doi.org/10.1111/j.1539-6975.2011.01423.x.
- Business Insurance. 2003. “Insurers Settle Surety Claims with JPMorgan Chase.” January. https://www.businessinsurance.com/insurers-settle-surety-claims-with-jpmorgan-chase/.
- CFO. 2002. “The Uncertainty of Surety.” CFO Magazine. https://www.cfo.com/news/the-uncertainty-of-surety/681629/.
- CFO. 2003. “Morgan, Insurers Settle on Enron Surety Bonds.” CFO Magazine, January. https://www.cfo.com/news/morgan-insurers-settle-on-enron-surety-bonds/681255/.
- CNBC. 2026. “Trump Tariffs Leave Importers with Record-Breaking $3.5 Billion U.S. Customs Bond Funding Shortfall.” February 12. https://www.cnbc.com/2026/02/12/trump-tariffs-us-customs-record-bond-funding-issues-flagged.html.
- Coface. 2026. “Insolvencies Are on the Rise Again Against a Backdrop of a Deteriorating Economic Climate.” June 11. https://www.coface.com/news-economy-and-insights/insolvencies-are-on-the-rise-again-against-a-backdrop-of-a-deteriorating-economic-climate.
- Foley & Lardner LLP. 2026. “What Every Multinational Should Know About the New Customs Enforcement Realities (Part I): Managing Rising Bond and Collateral Requirements.” June 18. https://www.foley.com/insights/publications/2026/06/what-every-multinational-should-know-about-the-new-customs-enforcement-realities-part-i-managing-rising-bond-and-collateral-requirements/.
- Guy Carpenter. 2023. “U.S. Surety Industry Overview.” Presentation to the Casualty Actuarial Society Seminar on Reinsurance, session C-2. https://www.casact.org/sites/default/files/2023-06/23_Reinsurance_C-2.pdf.
- hyperexponential. 2026. “Surety Insurance Pricing Guide.” https://www.hyperexponential.com/lob-pricing-factors/surety.
- J.P. Morgan Chase & Co. 2003. Form 8-K, Item 5, January 2. https://www.sec.gov/Archives/edgar/data/0000019617/000001961703000003/fh8k1203.htm.
- Liebenberg, Andre P., and David W. Sommer. 2008. “Effects of Corporate Diversification: Evidence from the Property–Liability Insurance Industry.” Journal of Risk and Insurance 75 (4): 893–919. https://doi.org/10.1111/j.1539-6975.2008.00290.x.
- Merchants Bonding Company. 2024. “SFAA Q3 Reveals Low Loss Ratio for Merchants.” https://www.merchantsbonding.com/about/news/sfaa-q3-reveals-low-loss-ratio-for-merchants.
- NAIC (National Association of Insurance Commissioners). 2025. 2024 Market Share Reports for Property/Casualty Groups and Companies. Kansas City: NAIC.
- Willis Re. 2026. Built for Cycles: Heading into 1/1 2027. Credit, Surety and Political Risk Market View, October 30. https://www.willisre.com/news-and-insights/built-for-cycles-heading-into-1-1-2027/.
- WTW. 2024. “Insurance Marketplace Realities 2024 Spring Update: Surety.” May. https://www.wtwco.com/en-us/insights/2024/05/insurance-marketplace-realities-2024-spring-update-surety.